
Pricing Asian Options Under A General Jump Diffusion Model

Pricing Asian Options under a General Jump Diffusion Model

(PDF) Pricing Asian Options Under a Hyper-Exponential Jump Diffusion Model

(PDF) Option Pricing Under a Double Exponential Jump Diffusion Model

Pricing of a Binary Option Under a Mixed Exponential Jump Diffusion Model

Pricing of a Binary Option Under a Mixed Exponential Jump Diffusion Model

Pricing of a Binary Option Under a Mixed Exponential Jump Diffusion Model

(PDF) Option pricing under jump diffusion model (2023) | Qian Li

(PDF) Option Pricing in a Regime Switching Jump Diffusion Model

Cai - and - Kou - 2012 - Pricing Asian Options Under A Hyper ...
[2105.06999] Actuarial strategy for pricing Asian options under a mixed ...
Advertisement Space (300x250)
Pricing of Some Exotic Options under Jump Diffusion and Stochastic ...

Pricing vulnerable options under a jump-diffusion model with fast mean ...

Pricing vulnerable options under a jump-diffusion model with fast mean ...
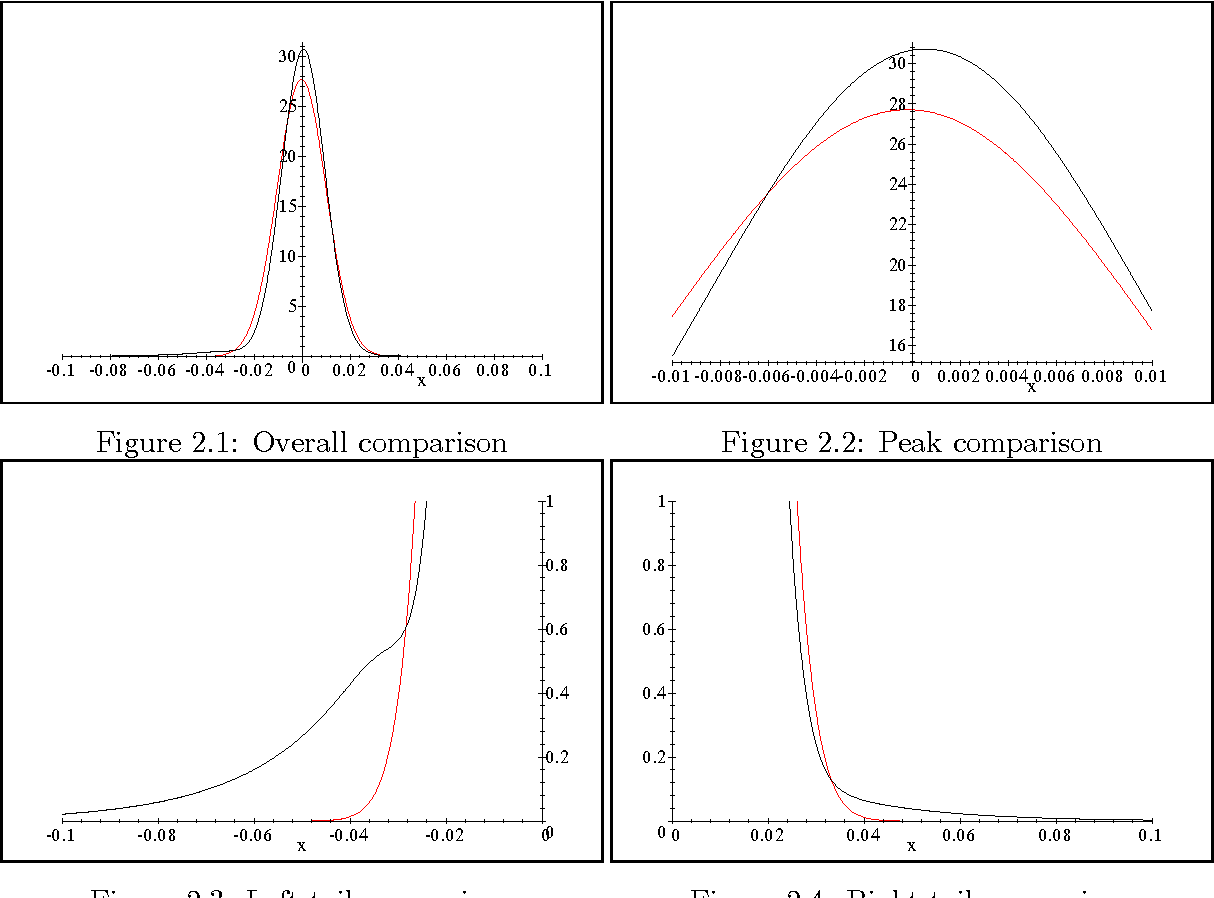
Figure 2.2 from A jump diffusion model for option pricing with three ...

Option Pricing under the Jump Diffusion and Multifactor Stochastic ...

4. Minimum of 2 put option under Merton's jump diffusion model ...

Efficient Asian option pricing under regime switching jump diffusions ...
(PDF) Pricing Asian Options for Jump Diffusions

Pricing Discretely Monitored Asian Options Under Regime-Switching and ...

(PDF) Efficient Asian option pricing under regime switching jump ...
Advertisement Space (336x280)

(PDF) Pricing Options in Jump Diffusion Models Using Mellin Transforms

(PDF) Option Pricing under the Jump Diffusion and Multifactor ...

(PDF) A jump-diffusion model for pricing electricity under price-cap ...
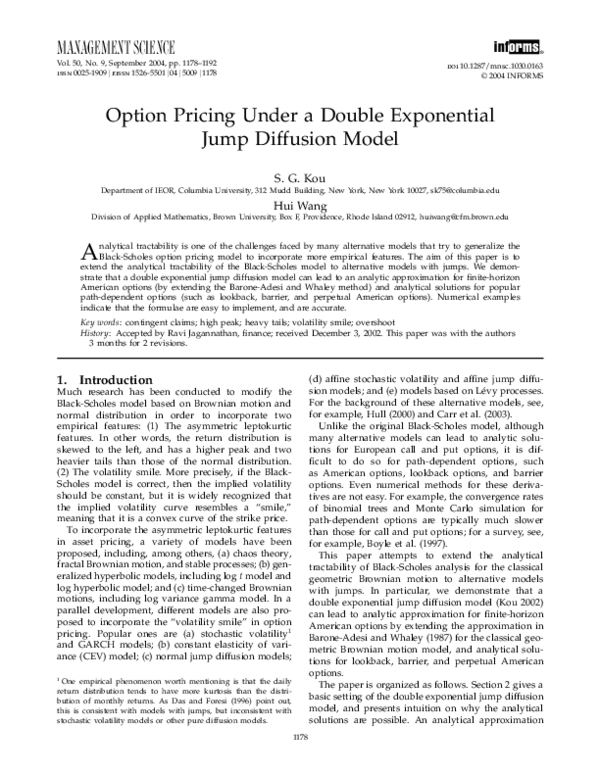
(PDF) Option pricing under a double-exponential jump-diffusion model ...
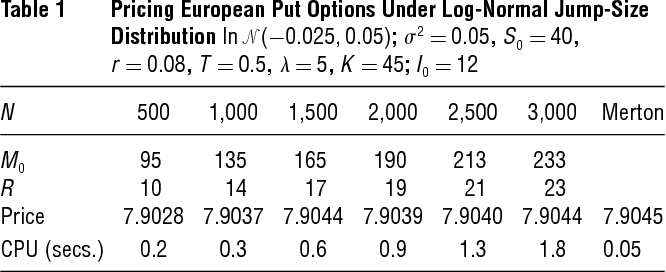
Table 1 from Option Pricing for a Jump-Diffusion Model with General ...

(PDF) Pricing Asian Power Options under Jump-Fraction Process

Option Pricing under the Jump Diffusion and Multifactor Stochastic ...

(PDF) Pricing of Parisian Options for a Jump-Diffusion Model with Two ...

(PDF) A two asset option pricing problem in jump diffusion models ...

(PDF) A Jump Diffusion Model with Fast Mean-Reverting Stochastic ...
Advertisement Space (336x280)

(PDF) Pricing discrete path-dependent options under a double ...
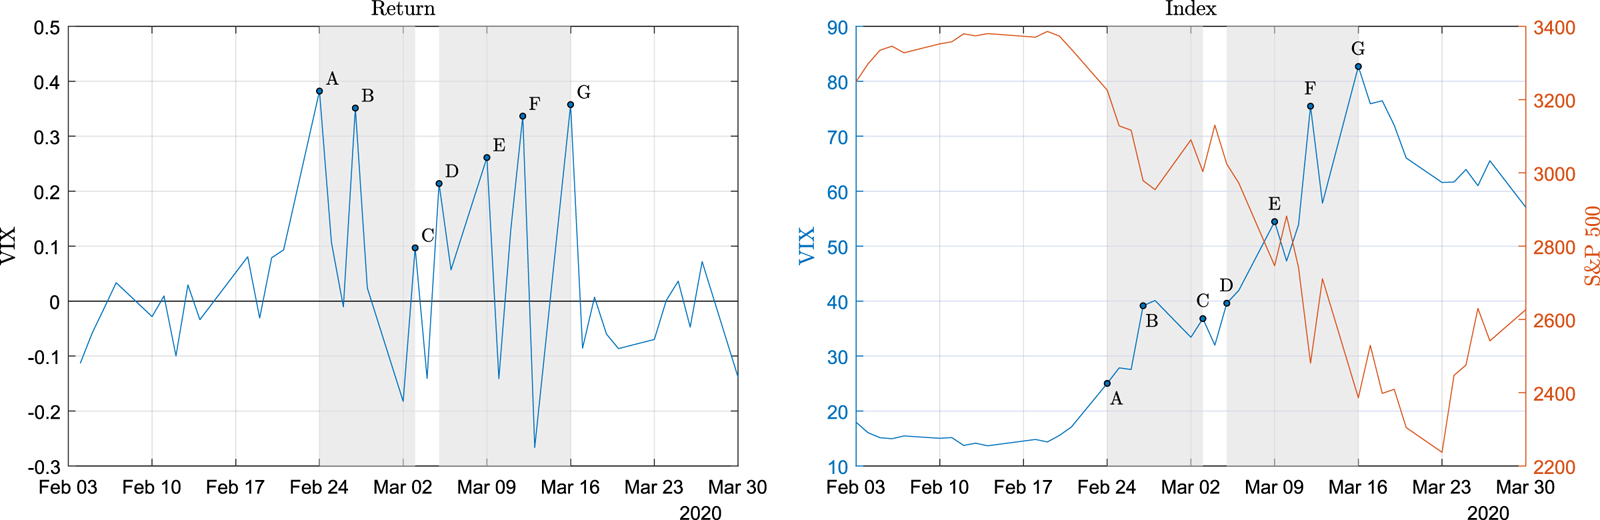
Option pricing under a double-exponential jump-diffusion model with ...

Option Pricing and Portfolio Optimization under a Multi-Asset Jump ...

(PDF) Risk-minimizing option pricing under a Markov-modulated jump ...
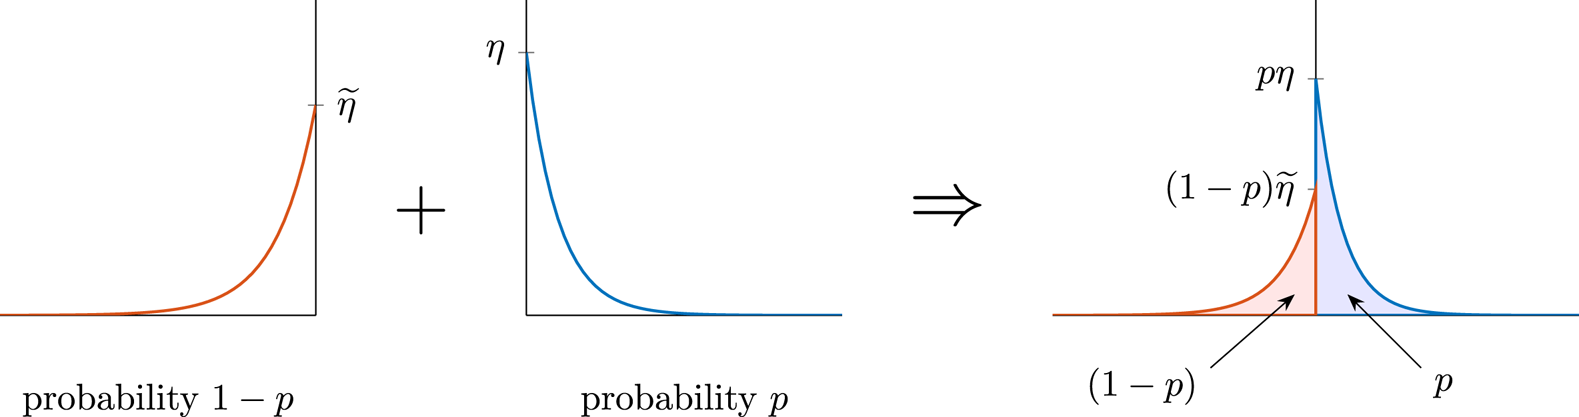
Option pricing under a double-exponential jump-diffusion model with ...

Commodity Asian option pricing and simulation in a 4-factor model with ...