
Solved Consider A Time Series Model Xt01twt Where Wt Cheggcom

Solved 5. Consider a time series model Xt=Wt+C(∑s=−∞t−1Ws) | Chegg.com

Solved Consider the time series model xt=αxt−1+wt where α is | Chegg.com
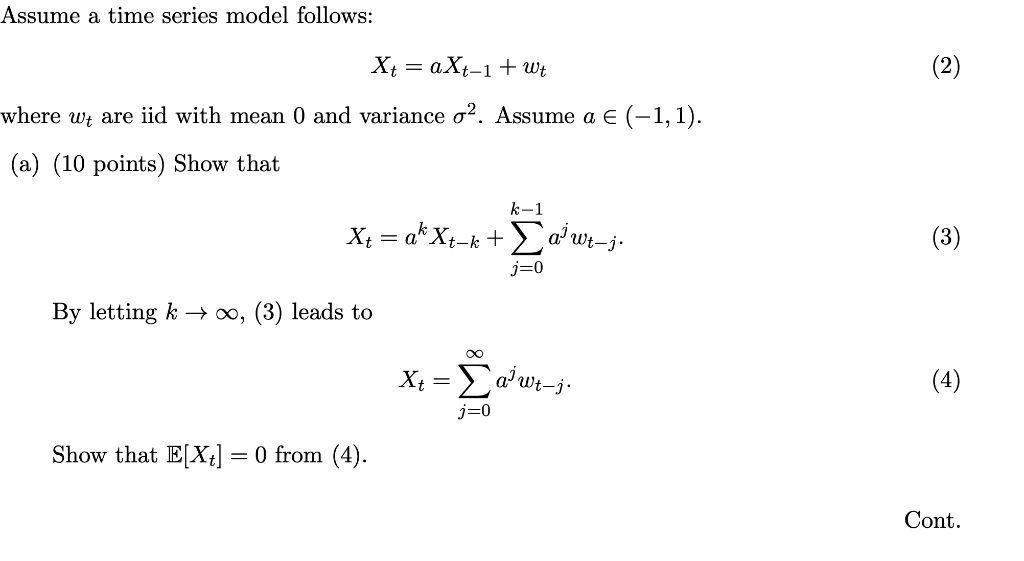
Solved Assume a time series model follows: Xt = aXt-1+ wt | Chegg.com
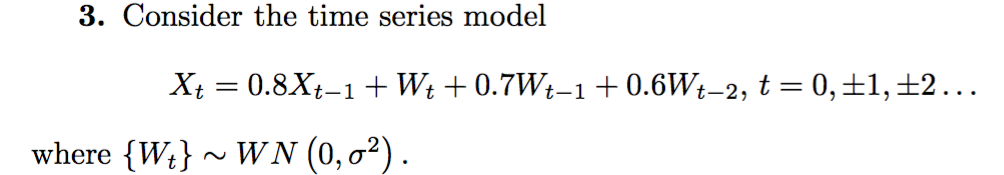
Solved 3. Consider the time series model where { .} ~ WN (0, | Chegg.com
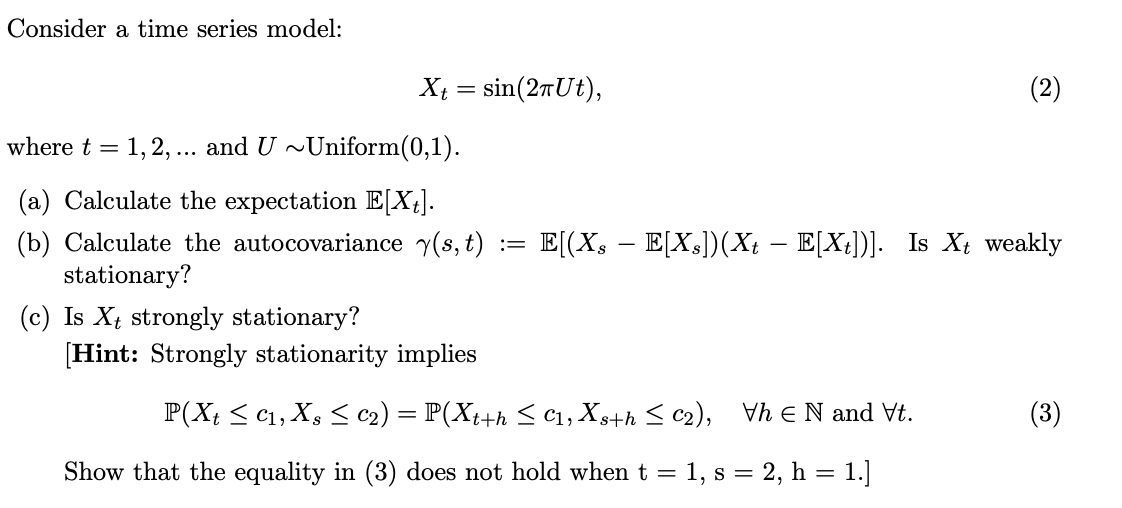
Solved Consider a time series model: Xt=sin(2πUt) where | Chegg.com

Solved (a) Consider a time series regression model given as | Chegg.com
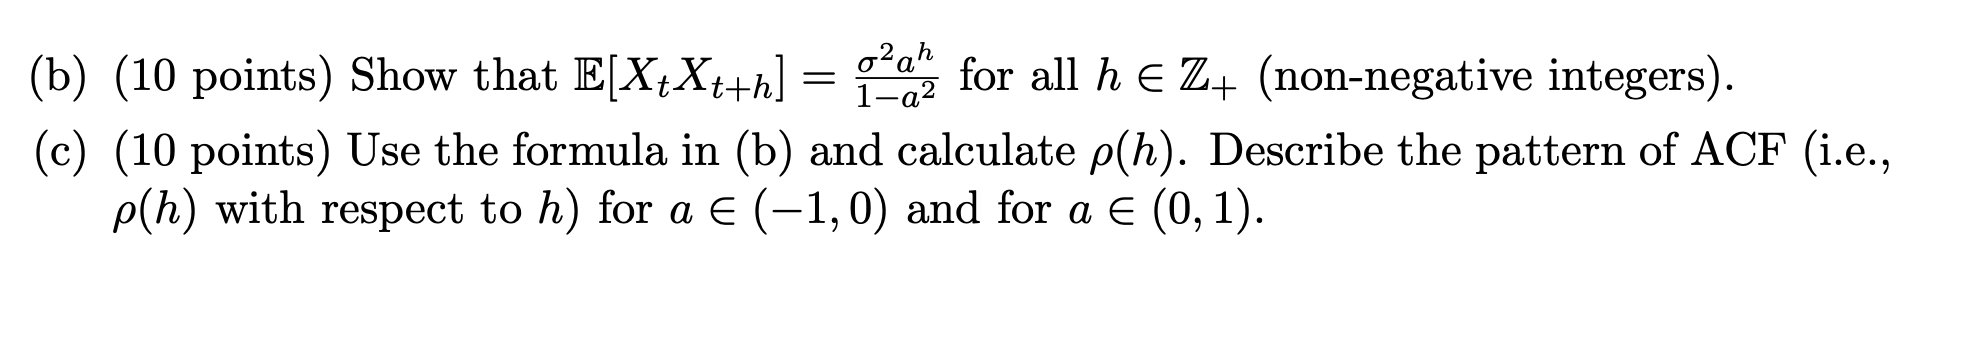
Solved Assume a time series model follows: Xt = aXt-1+ wt | Chegg.com

Solved Consider a time series {X1,X2,…,XT}, where | Chegg.com
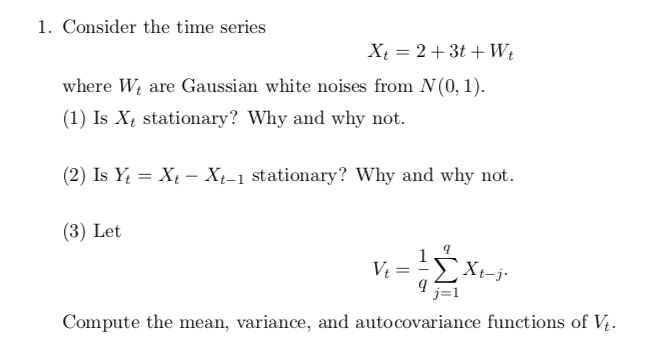
Solved 1. Consider the time series where Wt are Gaussian | Chegg.com
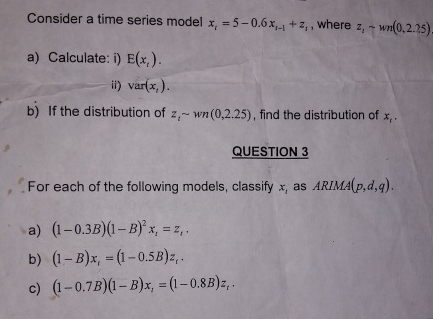
Solved Consider a time series model xt=5-0.6xt-1+zt, where | Chegg.com
Advertisement Space (300x250)
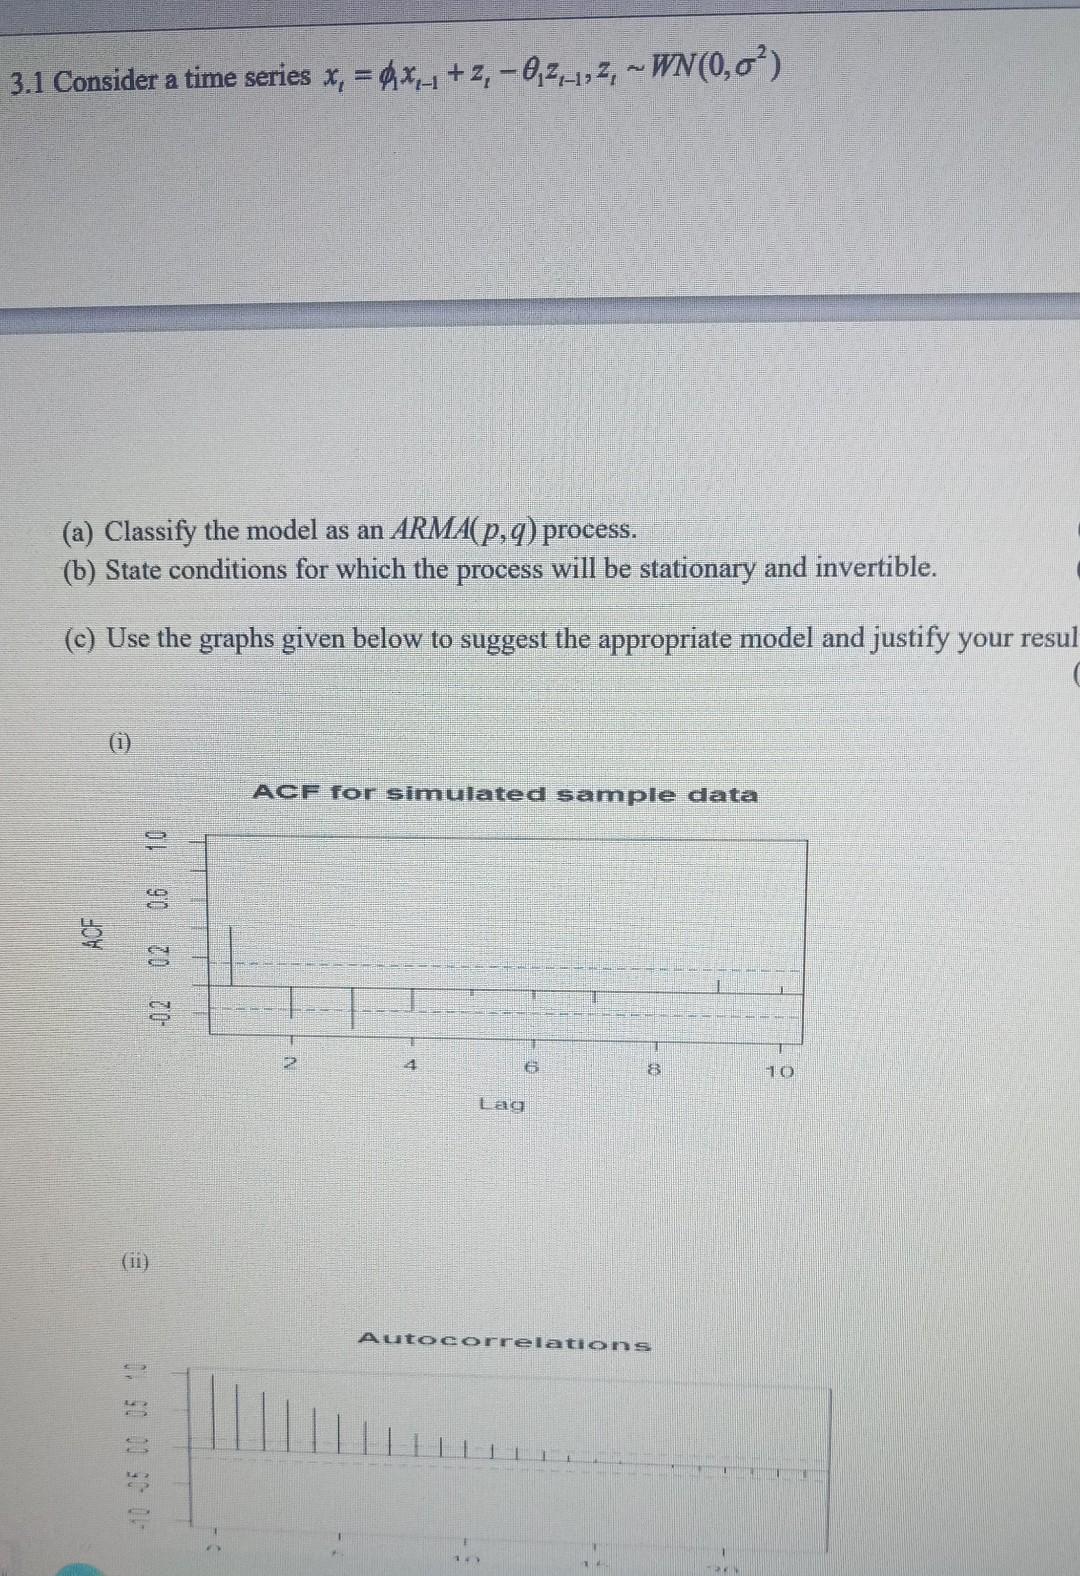
Solved 5.1 Consider a time series (1−B)xt=12+zt, where | Chegg.com
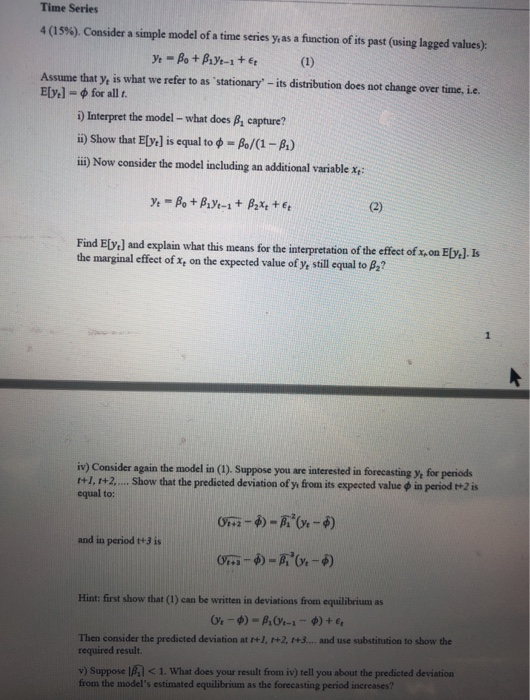
Solved Time Series 4 (15%) consider a simple model of a time | Chegg.com

Solved A time series model is given by xt=mt+εt where mt is | Chegg.com

Solved 1. Consider the following time series model Xt=μ+ϵt | Chegg.com
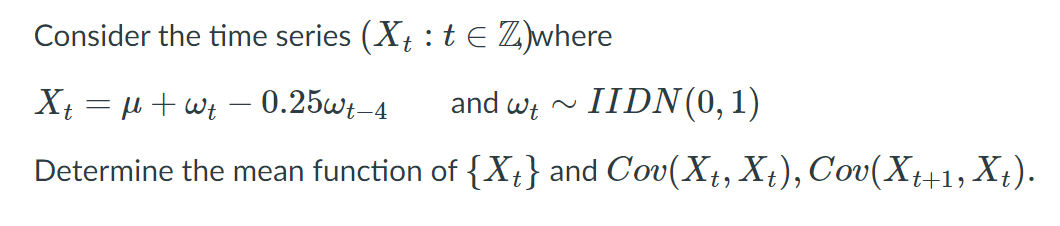
Solved Consider the time series (Xt:t E Z)where X+ = u + wt | Chegg.com

Solved 1. Consider the following time series model Xt=μ+ϵt | Chegg.com

Solved (a) Consider the following time series model for | Chegg.com
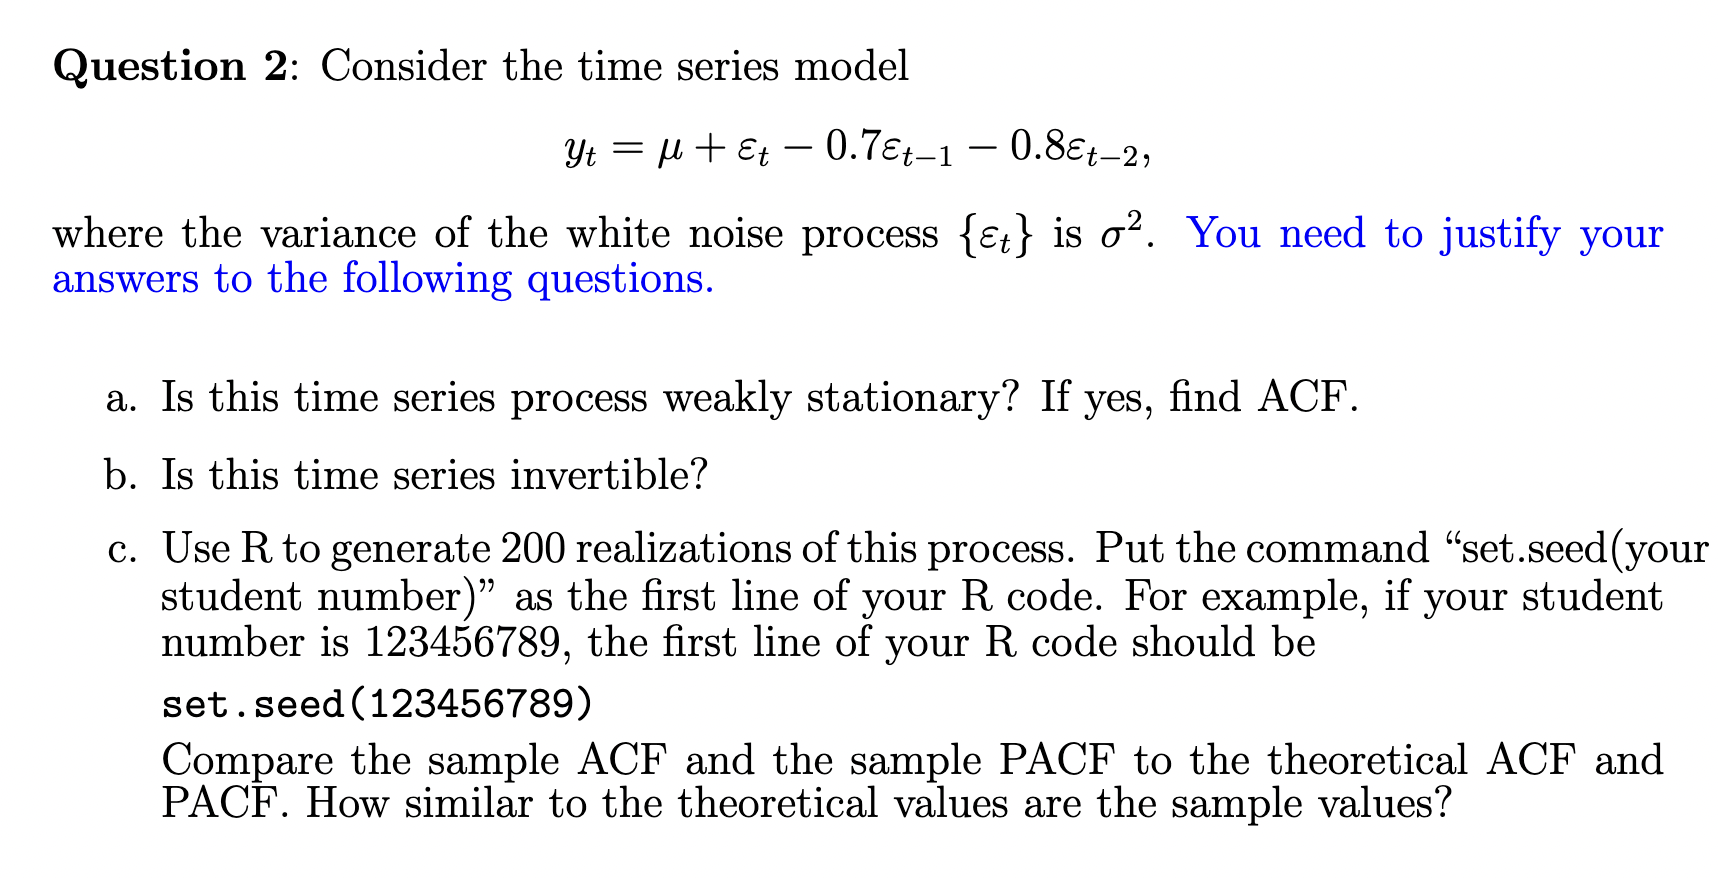
Solved Question 2: Consider the time series model Yt = u + | Chegg.com
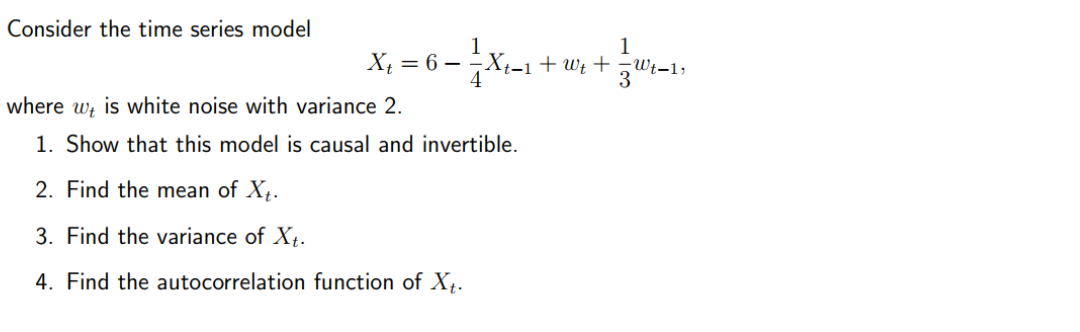
Solved 1 Wt-1 Consider the time series model X4 = 6 - - X:-1 | Chegg.com
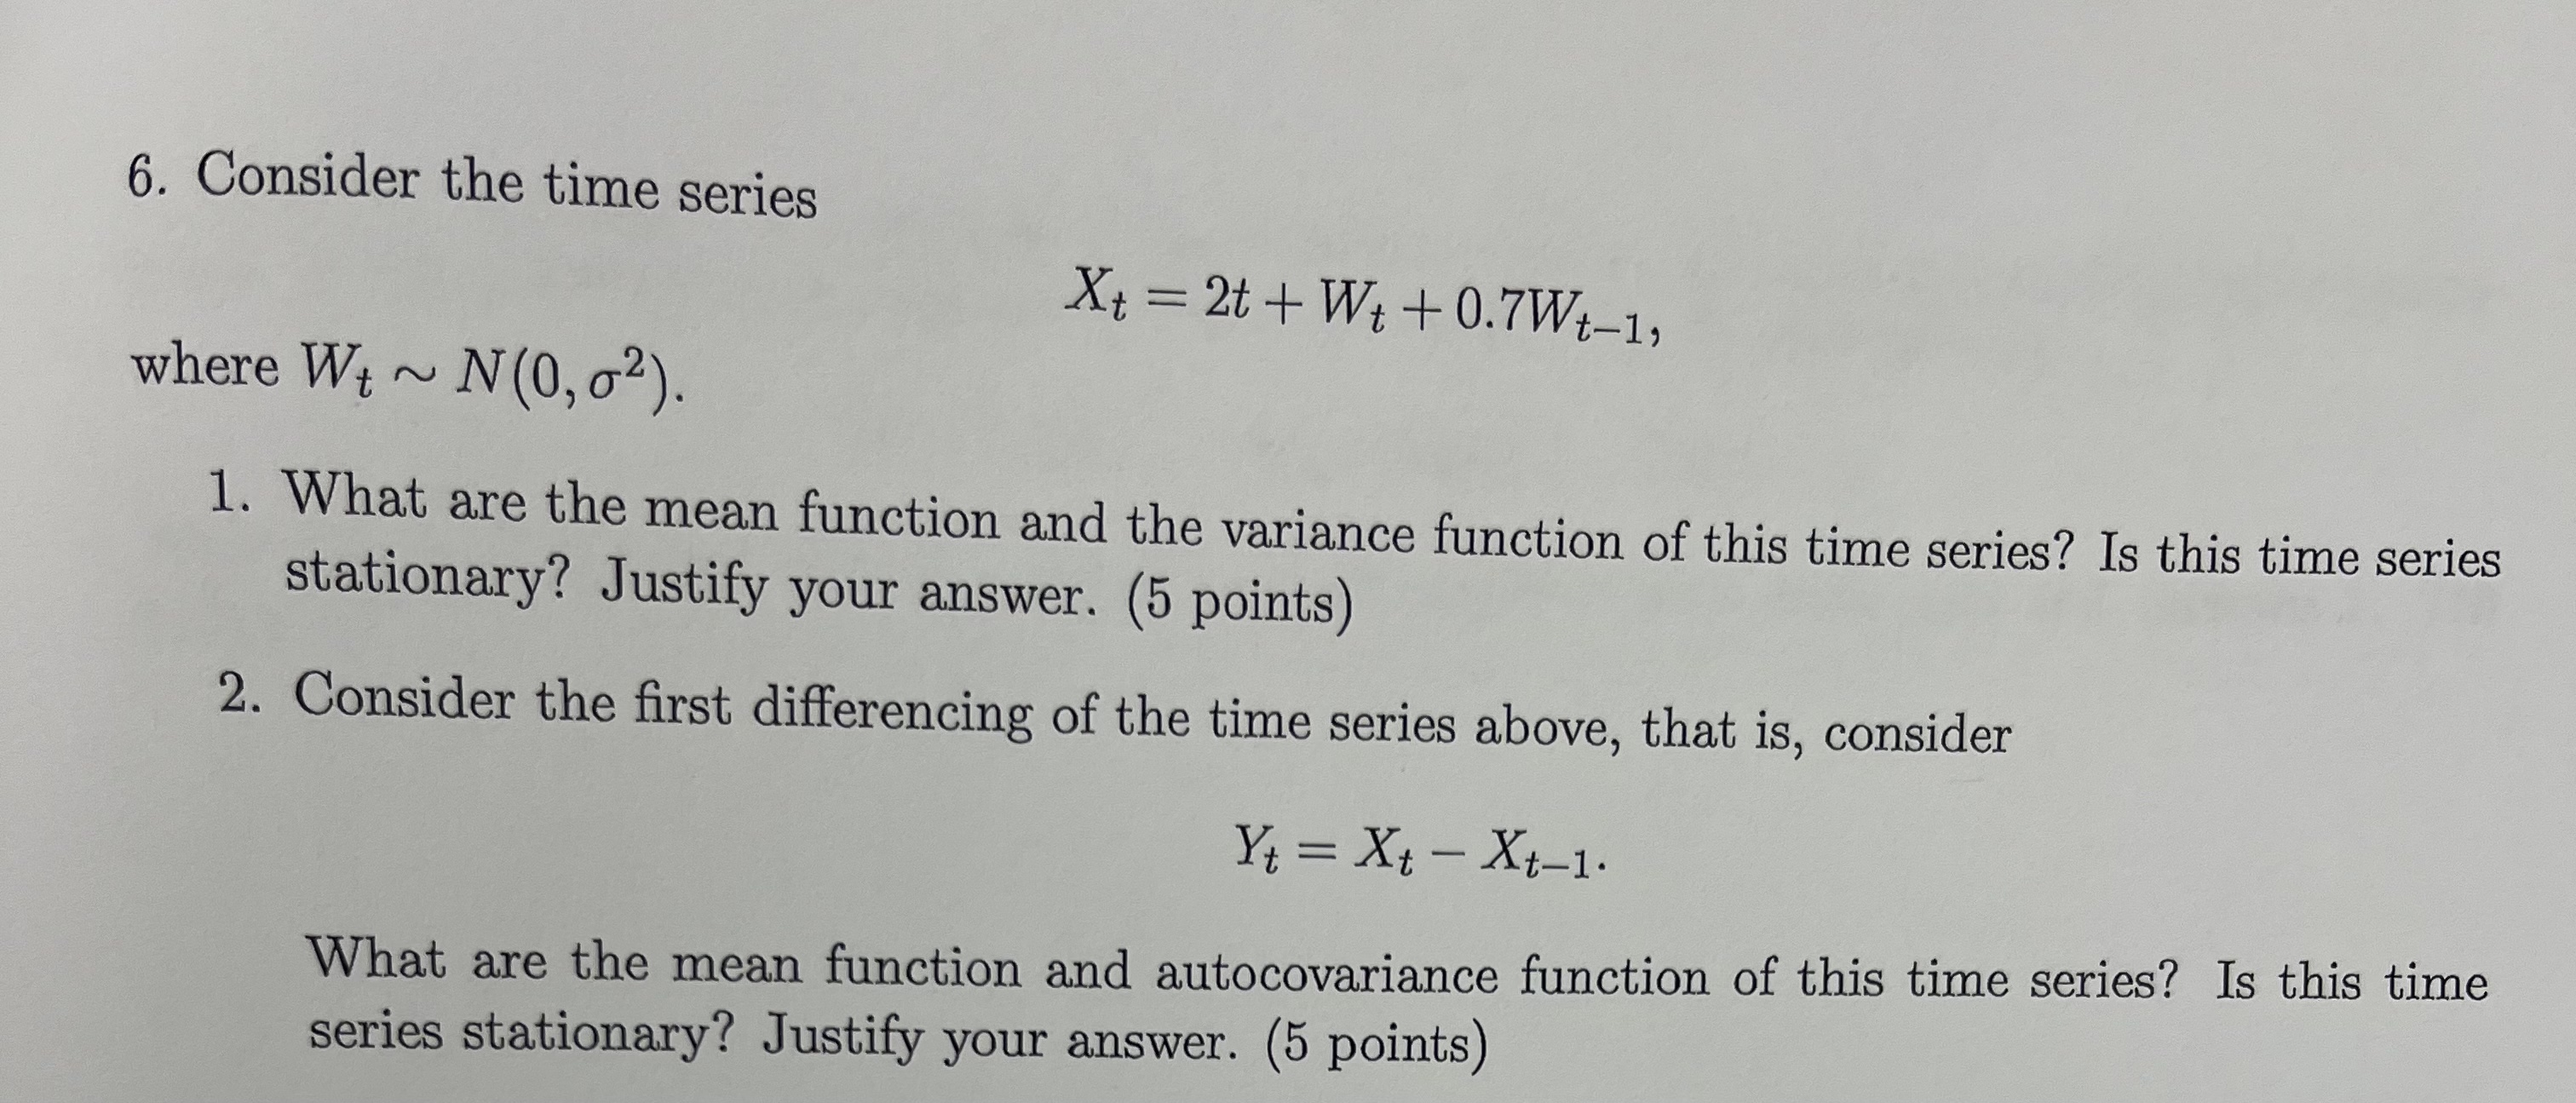
Solved 6. Consider the time series Xt=2t+Wt+0.7Wt−1 where | Chegg.com
Advertisement Space (336x280)
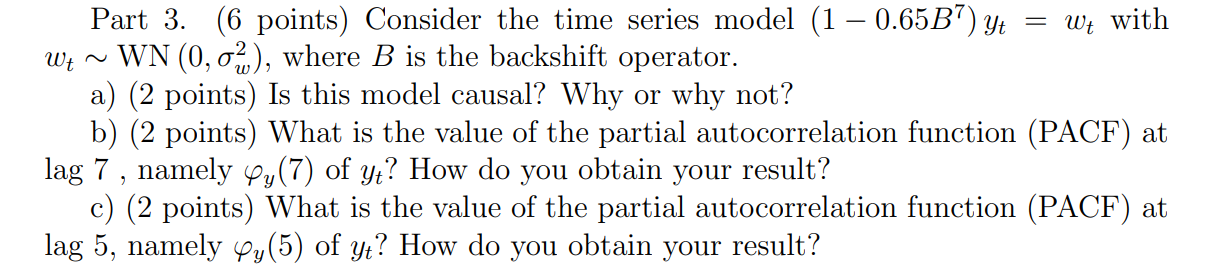
Solved Part 3. (6 points) Consider the time series model (1 | Chegg.com
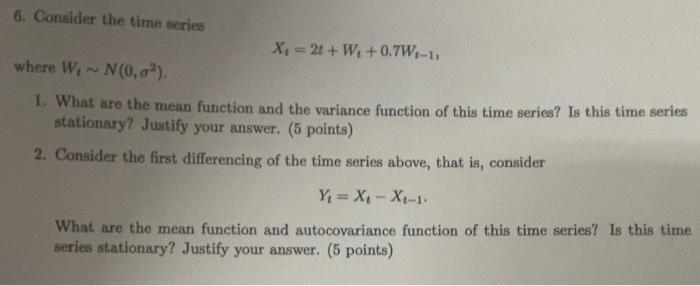
Solved 6. Consider the time series Xt=2t+Wt+0.7Wt−1 where | Chegg.com
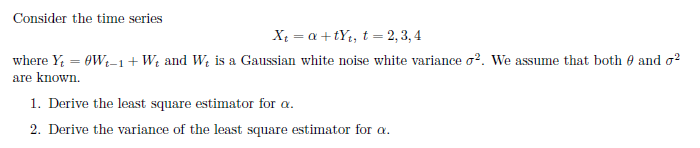
Solved Consider the time series X = a +tYt, t = 2, 3, 4 | Chegg.com
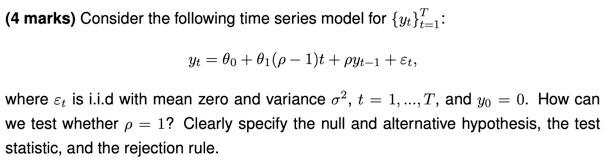
Solved (4 marks) Consider the following time series model | Chegg.com

1. Consider the time series Xt= 2 + 3t + Wt where Wt | Chegg.com
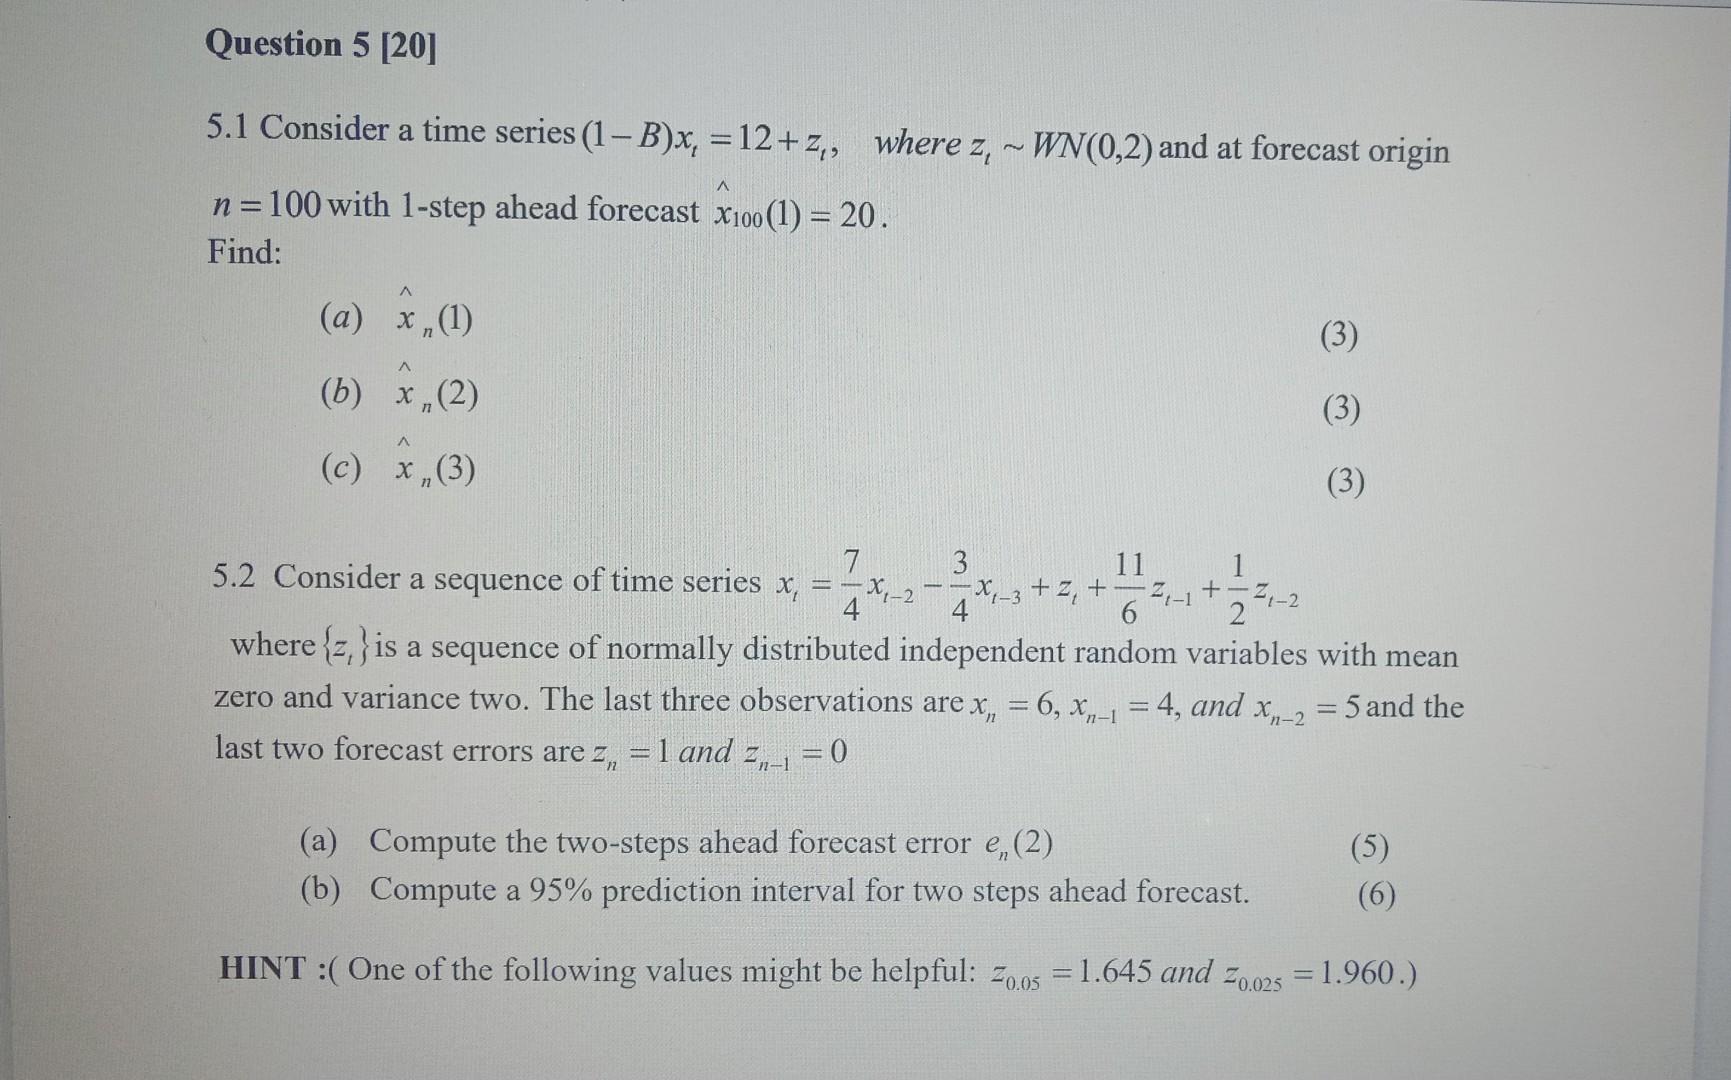
5.1 Consider a time series (1−B)xt=12+zt, where | Chegg.com
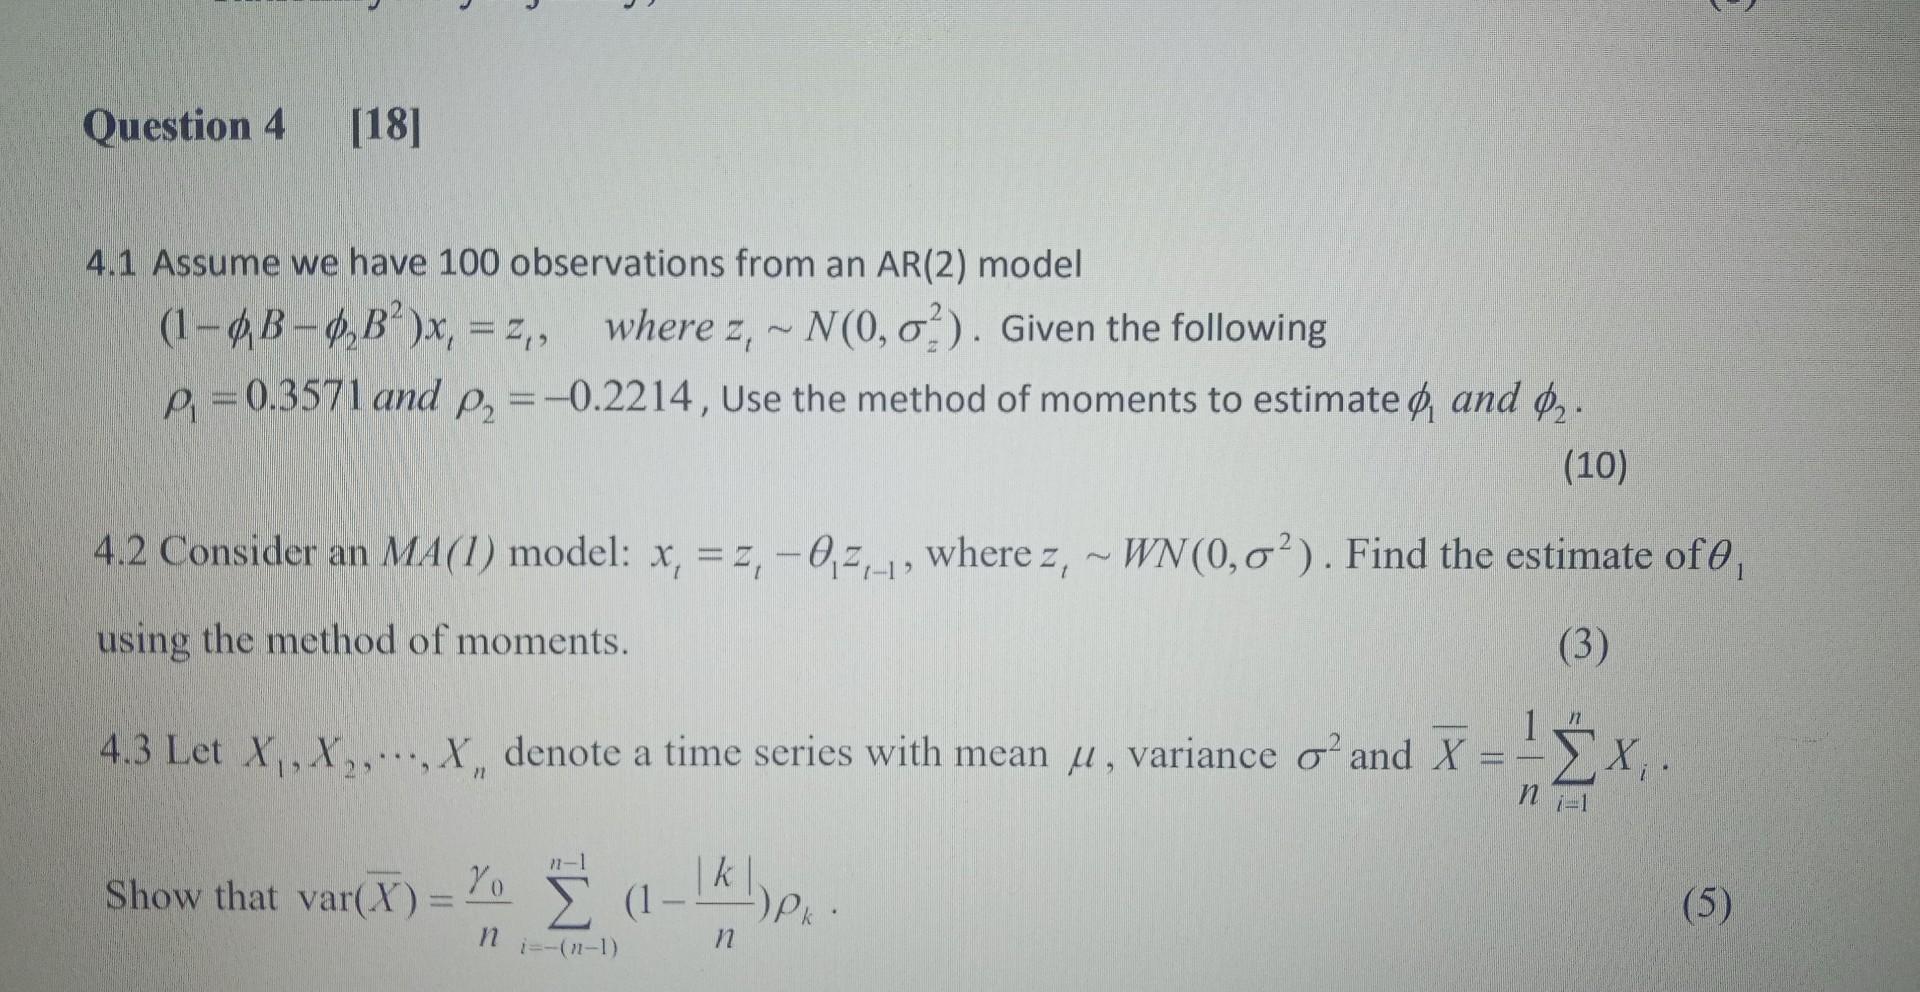
5.1 Consider a time series (1−B)xt=12+zt, where | Chegg.com
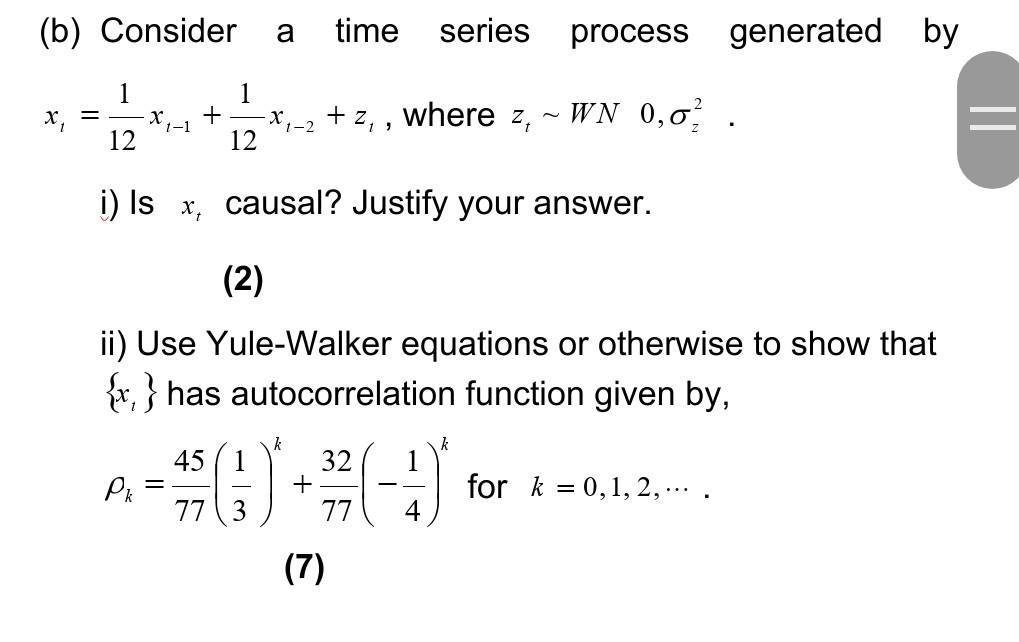
Solved (b) Consider a time series process generated by 1 = x | Chegg.com
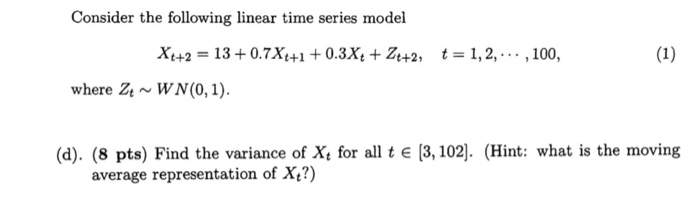
Solved Consider the following linear time series model Xt+2 | Chegg.com

Solved Consider a time – series model: X+ = 0.9X+ - 1 +Et , | Chegg.com
Advertisement Space (336x280)

Solved 3. Consider the time series Xt=β1+β2t+Wt where β1 and | Chegg.com
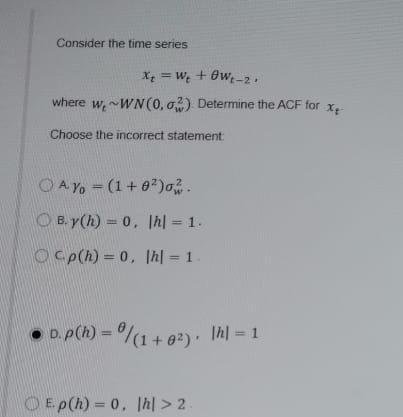
Solved Consider the time series xt=wt+θwt−2. where | Chegg.com
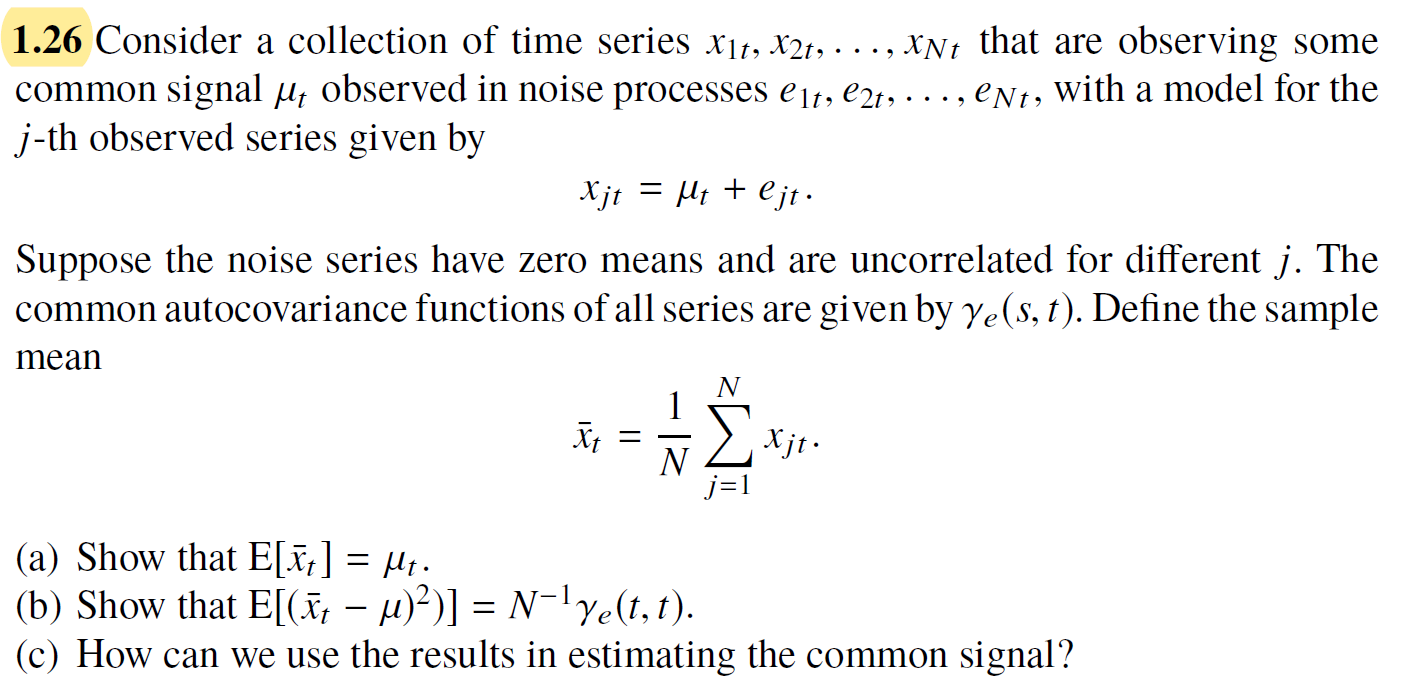
Solved 1.26 Consider a collection of time series X1t, X2t, | Chegg.com
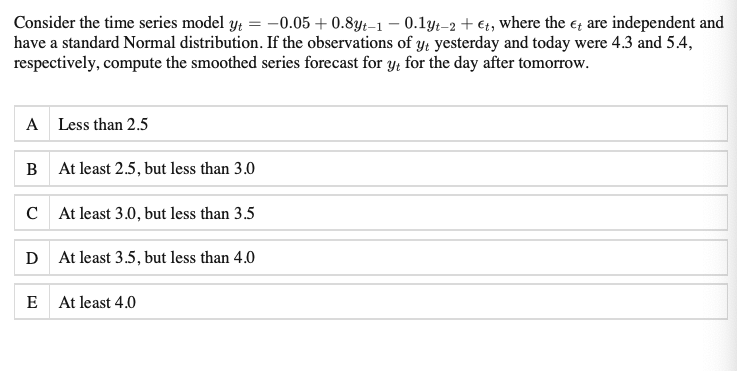
Solved Consider the time series model | Chegg.com
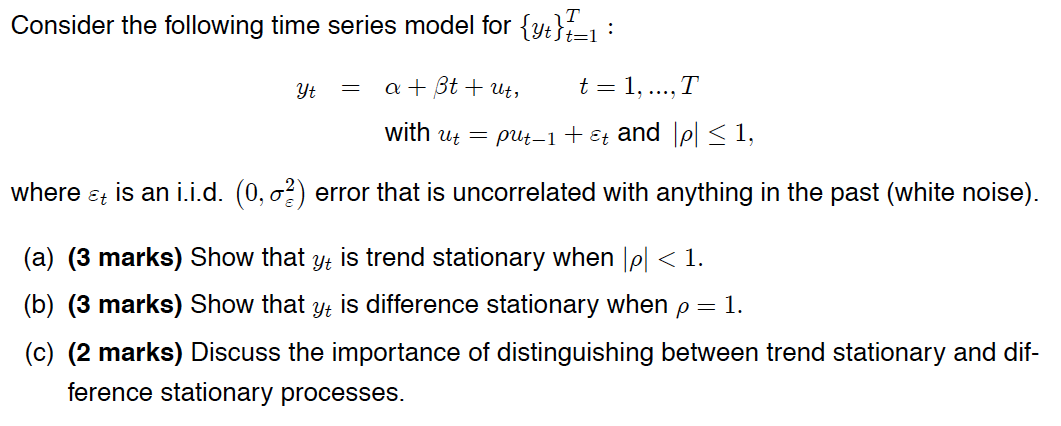
Solved Consider the following time series model for {3t}_1 : | Chegg.com
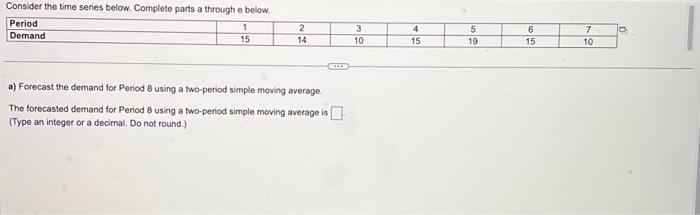
Solved Consider the time series below. Complete parts a and | Chegg.com