
004 Modelling Volatility Arch And Garch Models Pdf Econometrics

004 - Modelling Volatility - Arch and Garch Models | PDF | Econometrics ...

(PDF) Volatility Modelling using Arch and Garch Models (A Case Study of ...

(PDF) Modelling Stock Return Volatility using ARCH and GARCH Models

ARCH and GARCH Volatility Models | PDF | Vector Autoregression ...

Garch Models Materials - Modelling volatility - ARCH and GARCH models ...

ARCH and Garch Models - Mideling in econometrics - ARCH and GARCH ...

Understanding ARCH and GARCH Models for Financial Volatility | Course Hero

Modelling the Variance: ARCH and GARCH Models (Course Code: EDD) - Studocu

Modelling Volatility: Arch And Garch Models – HBYRGQ

Volatility Modeling with ARCH and GARCH | PDF | Time Series | Forecasting
Advertisement Space (300x250)

Arch and Garch: Modeling Volatility Dynamics | PDF | Teaching Methods ...

(PDF) Financial Econometrics Lecture 3: ARCH & GARCH models

Modelling Volatility Using GARCH Models: Evidence From Egypt and Israel ...
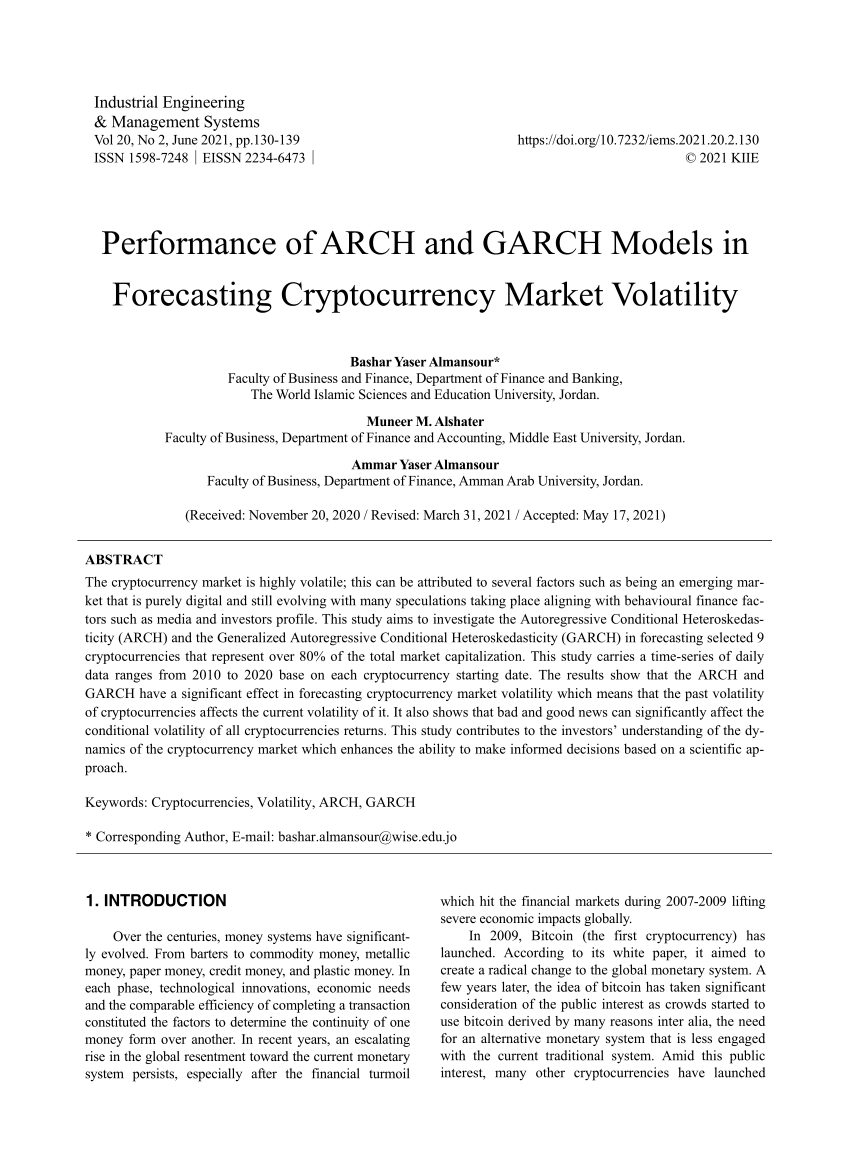
(PDF) Performance of ARCH and GARCH Models in Forecasting ...

GARCH Models for Volatility Forecasting | PDF

GARCH Models in Financial Econometrics | PDF | Black–Scholes Model ...

(PDF) Modelling and Estimation of Volatility Using ARCH/GARCH Models in ...

Arch & Garch Model | PDF | Errors And Residuals | Regression Analysis

ARCH and Garch Models - Lecture notes 23 - ARCH and GARCH Models A ...

(PDF) ESG Volatility Prediction Using GARCH and LSTM Models
Advertisement Space (336x280)

(PDF) Modelling Market Volatility with Univariate GARCH Models ...

(PDF) Modelling Volatility Dynamics of Cryptocurrencies Using GARCH Models
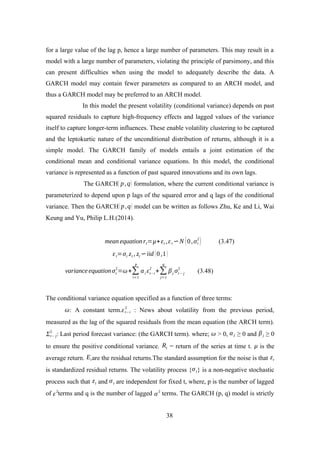
VOLATILITY ANALYSIS IN FINANCIAL TIME SERIES USING THE ARCH AND GARCH ...

The Order of GARCH Models (D) - Dynamic Models for Volatility and Heavy ...
ARCH and GARCH Models - Duke University - Economics

GARCH Models For Volatility Forecasting | PDF | Akaike Information ...

ECOM031 Financial Econometrics Lecture 4: Extending GARCH Models and ...

Understanding Volatility: ARCH and GARCH Models Explained | Course Hero

(PDF) Modelling Stock Market Volatility Using Univariate GARCH Models ...

Arch & Garch Models | PDF | Descriptive Statistics | Mathematical Finance
Advertisement Space (336x280)

GARCH Models for High-Frequency Volatility | PDF | Forecasting ...

(PDF) Modelling exchange rate volatility using GARCH models
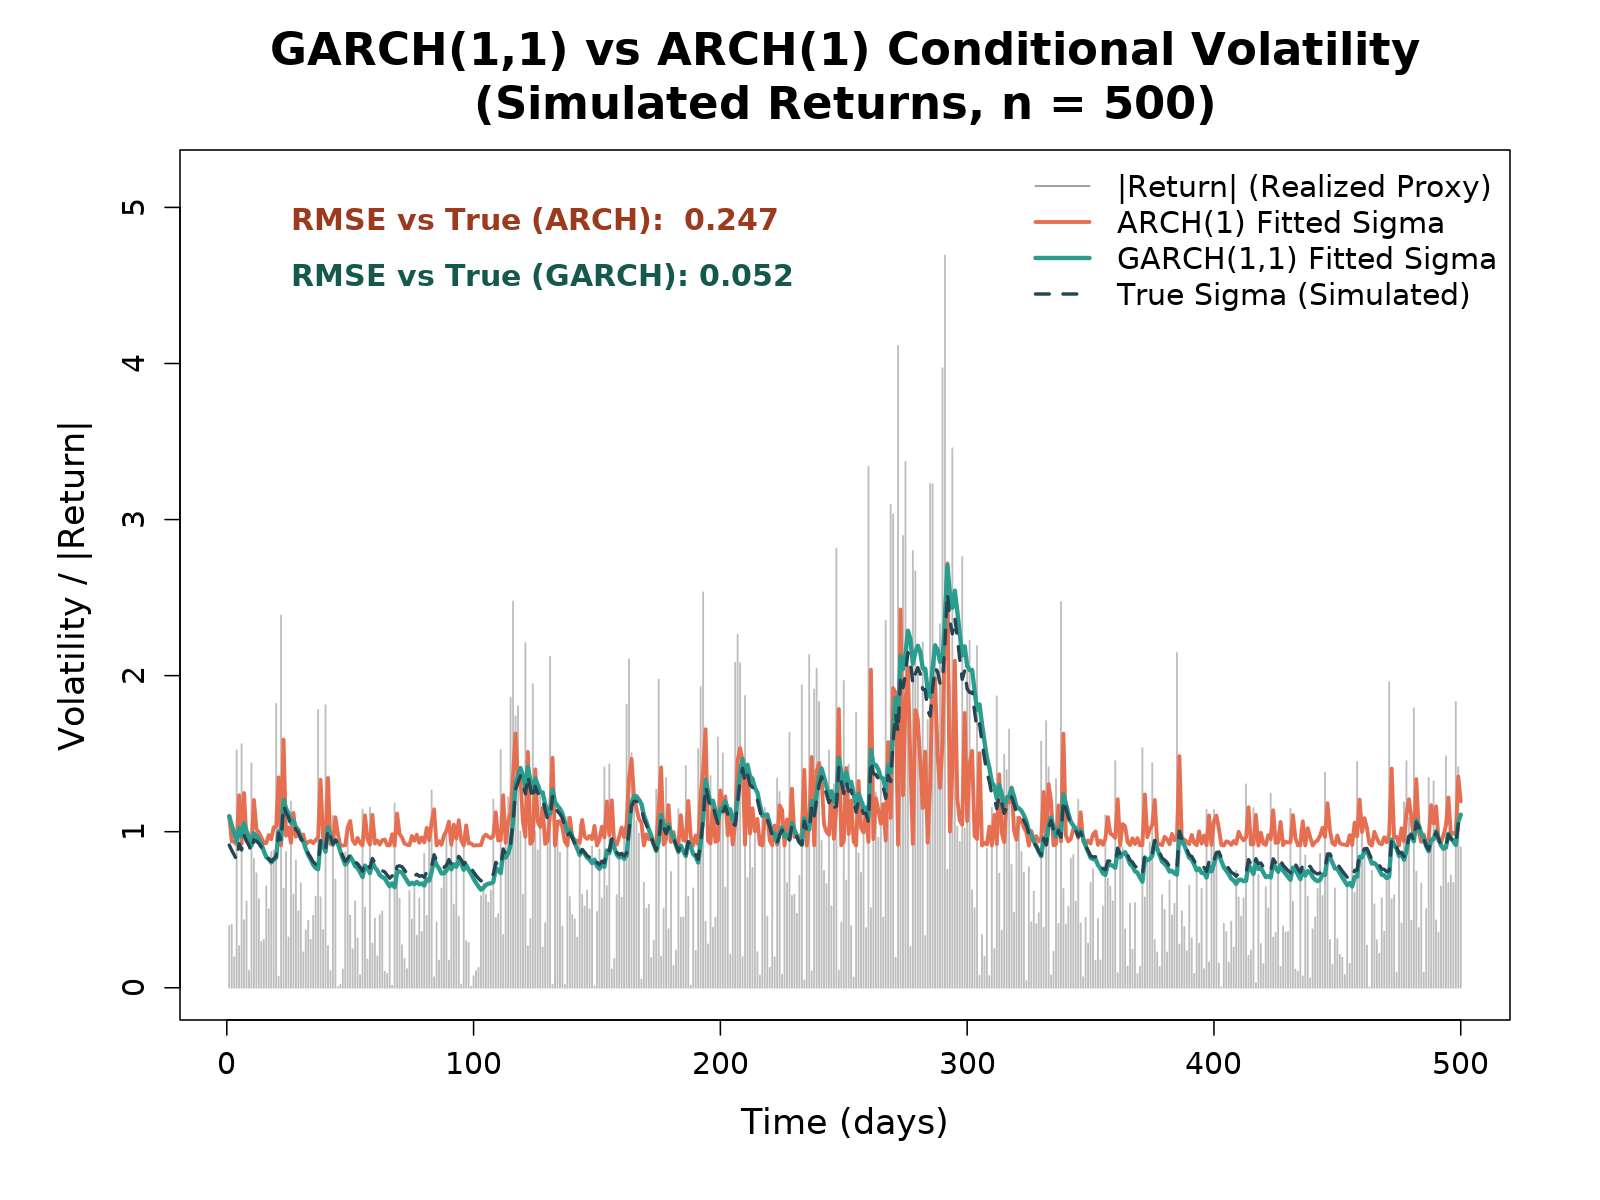
GARCH vs ARCH Volatility Models | MetricGate

GARCH Models in Financial Time Series | PDF | Econometrics | Estimation ...
(PDF) Modelling the Volatility of GHC_USD Exchange Rate Using Garch Model

(PDF) Asymmetric GARCH models on price volatility of agricultural ...