
Computation Of Option Greeks Under Hybrid Stochastic Volatility Models
Computation of option greeks under hybrid stochastic volatility models ...
(PDF) Computation of option greeks under hybrid stochastic volatility ...

(PDF) Asymptotic computation of Greeks under a stochastic volatility model

(PDF) Exact Simulation of Option Greeks under Stochastic Volatility and ...
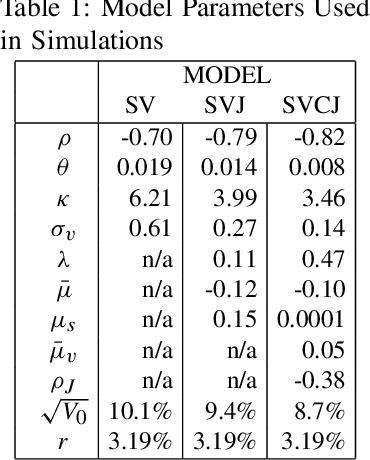
Table 1 from Exact simulation of option Greeks under stochastic ...
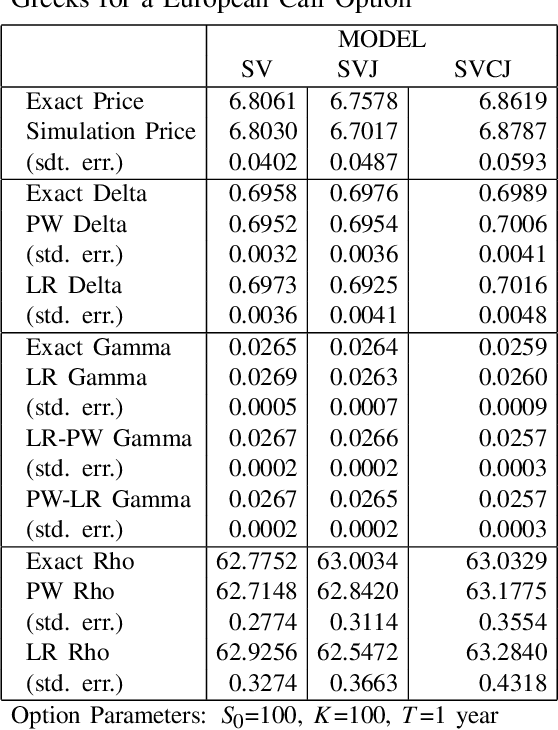
Table 1 from Exact simulation of option Greeks under stochastic ...

(PDF) Computations of Greeks in stochastic volatility models via the ...

Option Pricing under Double Stochastic Volatility Model with Stochastic ...
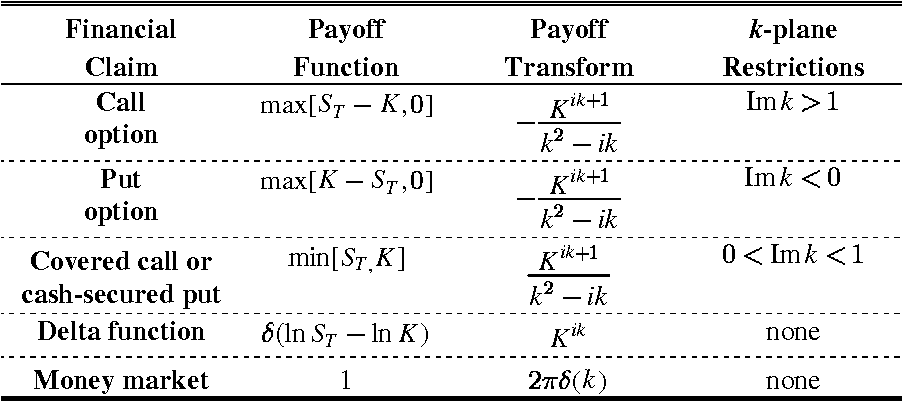
Table 2.1 from Option Valuation under Stochastic Volatility | Semantic ...

(PDF) Option Pricing under Double Stochastic Volatility Model with ...
Advertisement Space (300x250)

(PDF) Calibration of Stochastic Volatility Models on a Multi-Core CPU ...

Pricing European Options under Stochastic Volatility Models: Case of ...

(PDF) Pricing Parisian Option under a Stochastic Volatility Model

(PDF) Computation of the Greeks in Black-Scholes-Merton and Stochastic ...

Pricing European Options under Stochastic Volatility Models: Case of ...

(PDF) Computation of the Delta of European Options Under Stochastic ...

(PDF) Turbo Warrants under Hybrid Stochastic and Local Volatility

Pricing European Options under Stochastic Volatility Models: Case of ...
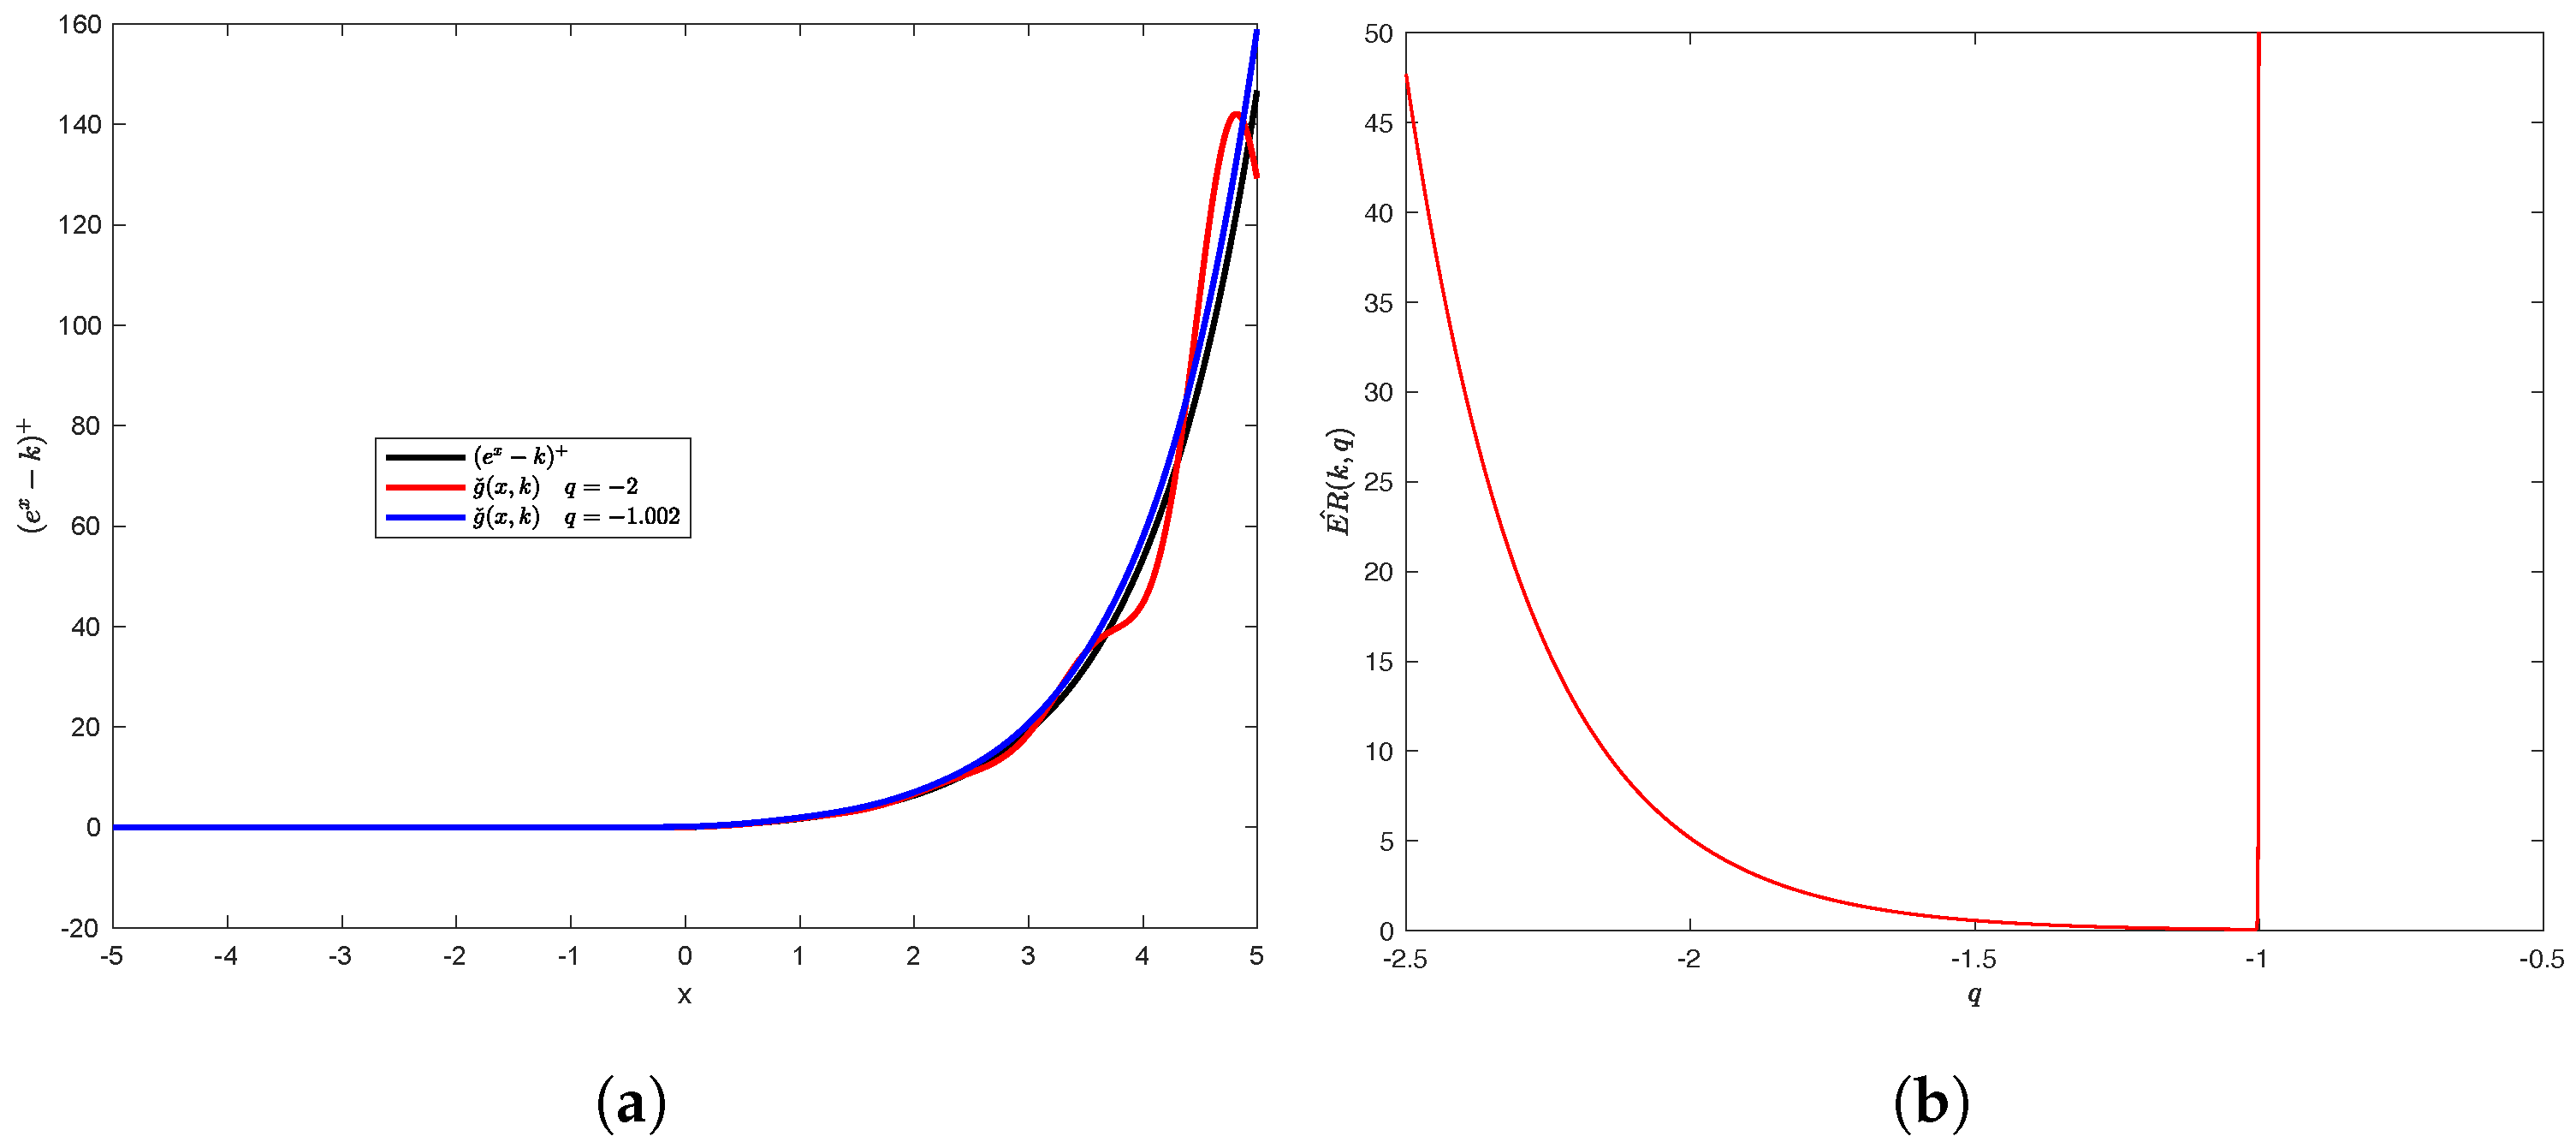
Pricing European Options under Stochastic Volatility Models: Case of ...
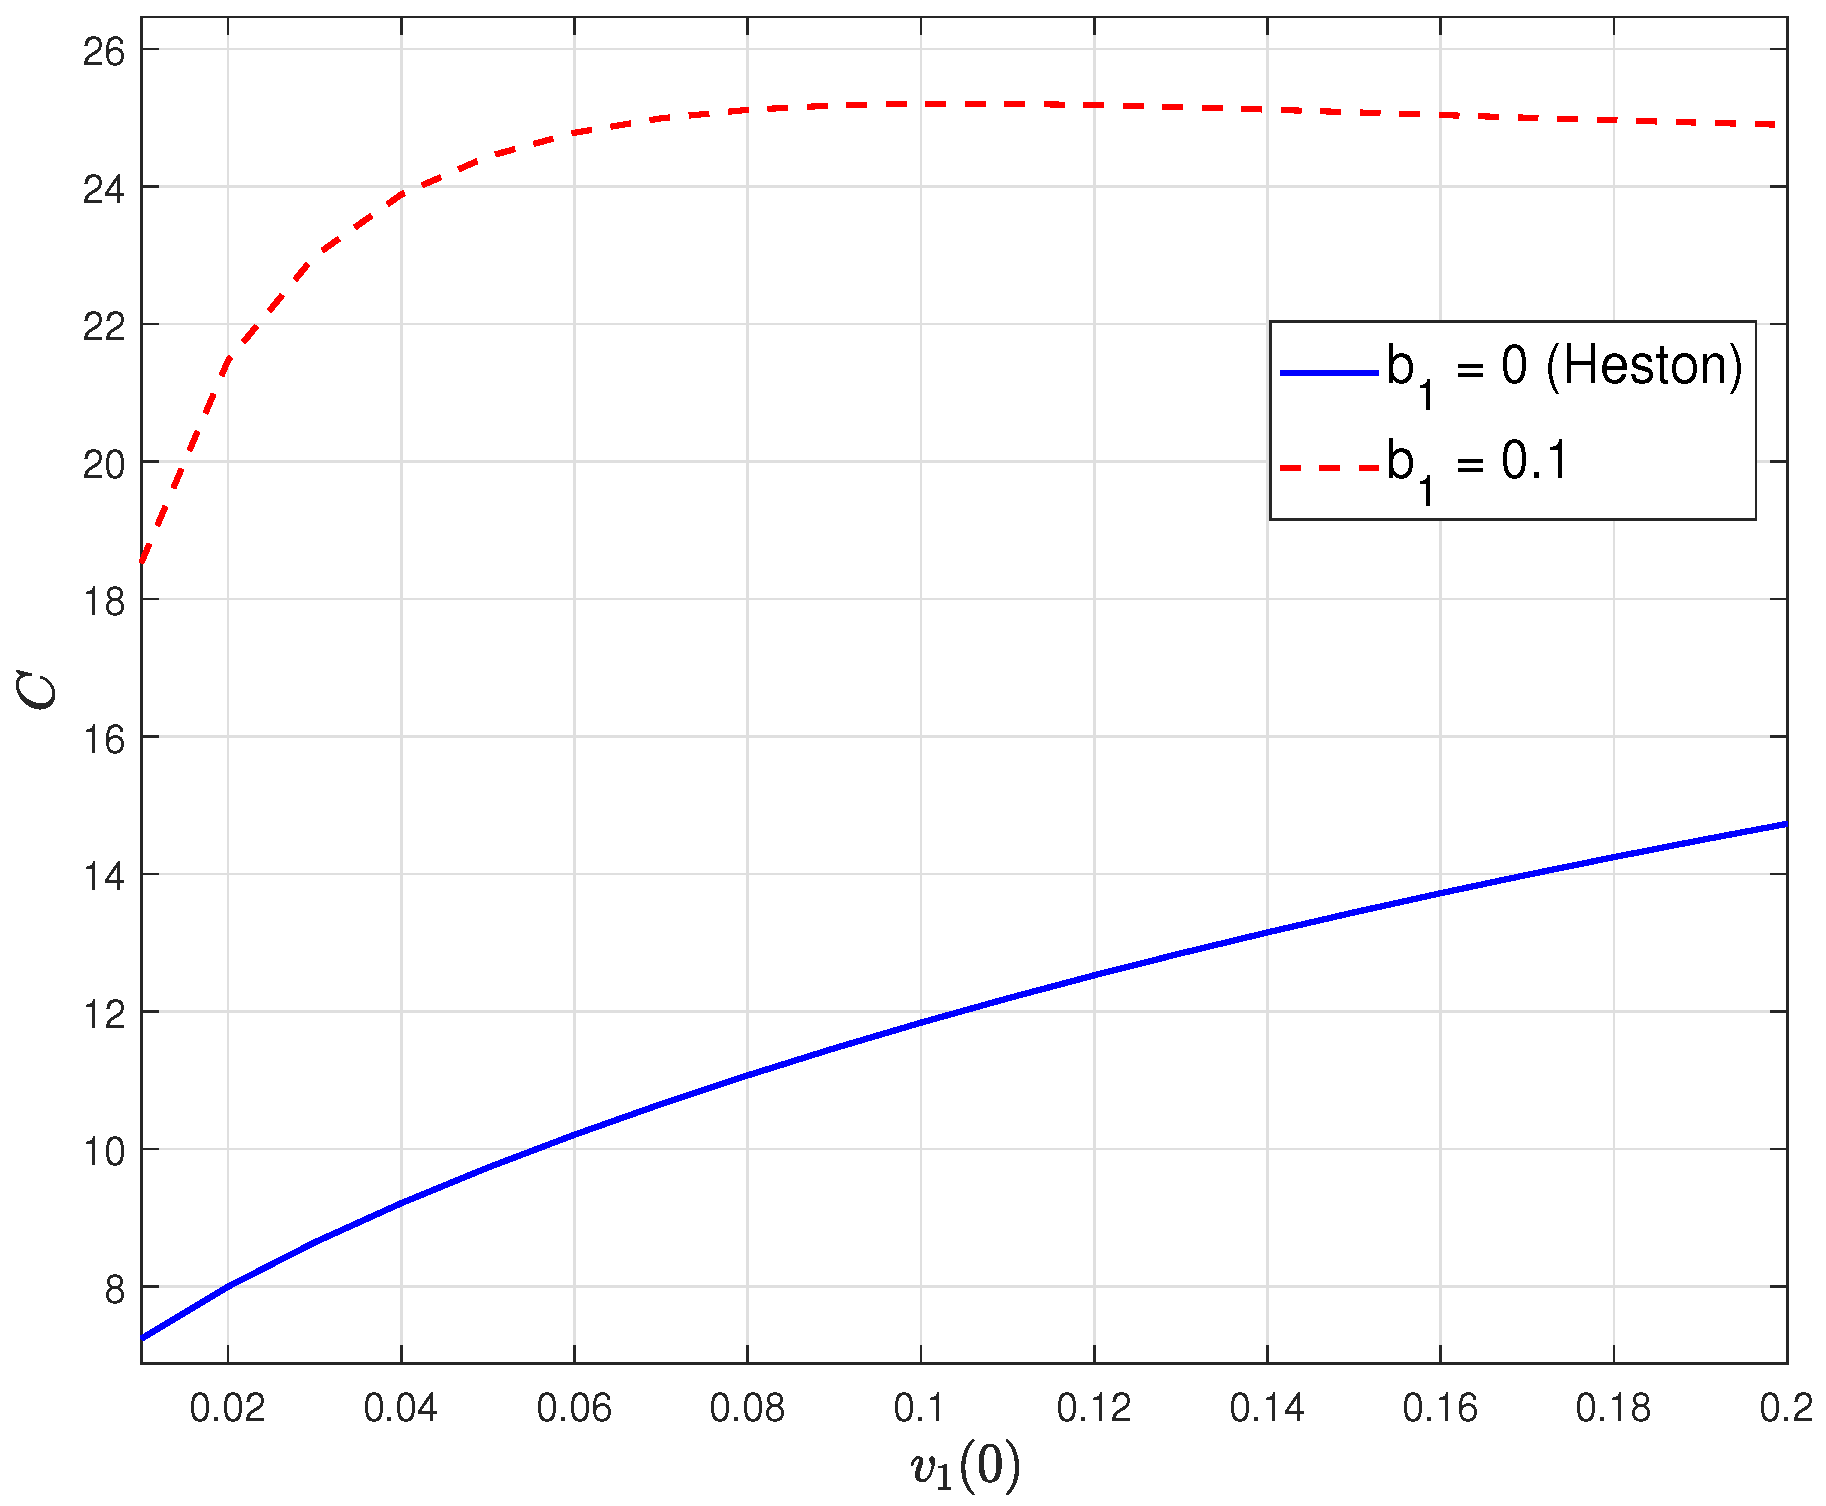
Vulnerable Option Pricing Under the 4/2 Stochastic Volatility Model
Advertisement Space (336x280)

(PDF) Pricing Variance Swaps in a Hybrid Model of Stochastic Volatility ...

Pricing European Options under Stochastic Volatility Models: Case of ...

Pricing European Options under Stochastic Volatility Models: Case of ...

Pricing Path-Dependent Options under Stochastic Volatility via Mellin ...

Analytically Pricing a Vulnerable Option under a Stochastic Liquidity ...

Option Pricing in the Heston Stochastic Volatility Model: An Empirical ...

Analytically Pricing a Vulnerable Option under a Stochastic Liquidity ...

Analytically Pricing a Vulnerable Option under a Stochastic Liquidity ...
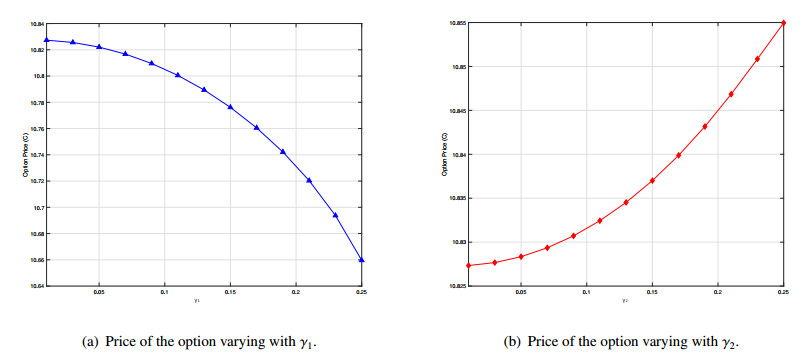
Analytical valuation of vulnerable options under a stochastic ...

On the Class of Risk Neutral Densities under Heston’s Stochastic ...
Advertisement Space (336x280)

Volatility Comparison between Stochastic Volatility Models | Download ...

Volatility Comparison between Stochastic Volatility Models | Download ...

A simulation of the stochastic volatility model described in example 4 ...

(PDF) Pricing European Options under Stochastic Volatility Models: Case ...
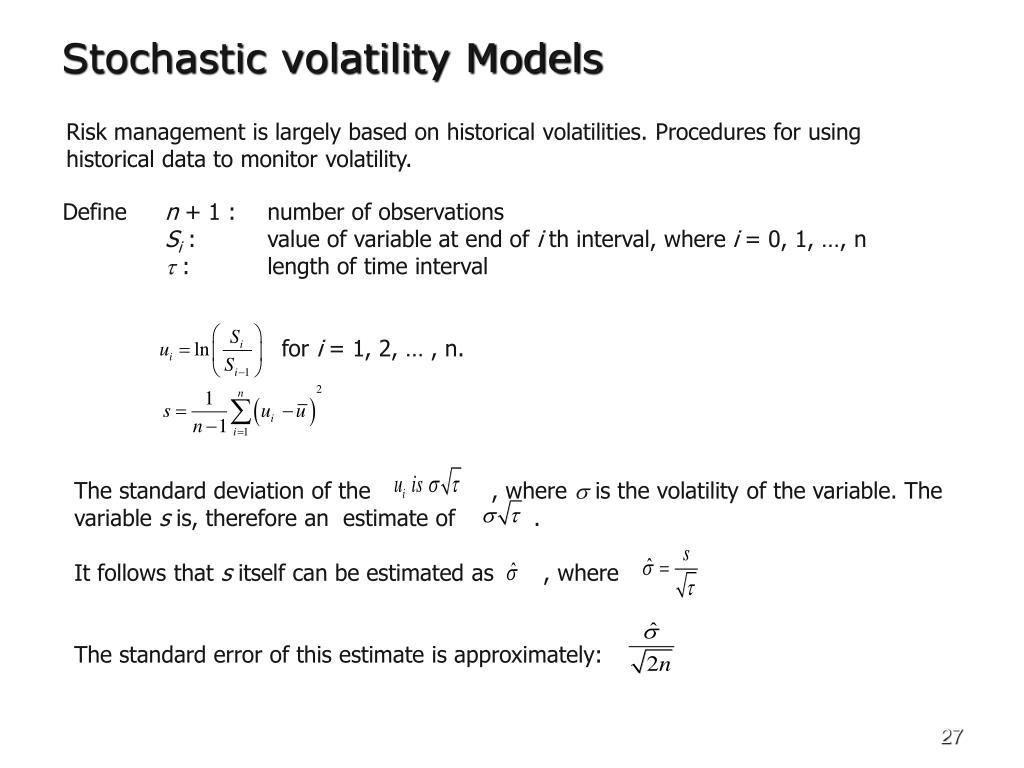
PPT - Market Risk Management using Stochastic Volatility Models ...
(PDF) Application of the Malliavin Calculus for Computation of Greeks ...