
Pdf Testing Volatility Spillovers Using Garch Models In The Japanese

(PDF) Testing volatility spillovers using GARCH models in the Japanese ...

(PDF) TESTING VOLATILITY CHANGES USING GARCH MODELS IN THE CASE OF ...

(PDF) Evaluating the Efficacy of GARCH Models in Forecasting Volatility ...

Volatility spillovers using different GARCH models | Download ...

Forecasting Stock Market Volatility Using Nonlinear) Garch Models | PDF
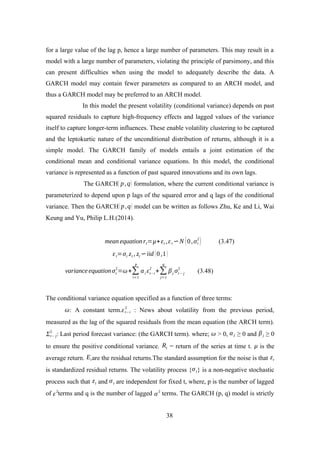
VOLATILITY ANALYSIS IN FINANCIAL TIME SERIES USING THE ARCH AND GARCH ...

(PDF) Testing GARCH and RV Exchange Rate Volatility Models using Hinich ...

GARCH Models For Volatility Forecasting | PDF | Akaike Information ...

(PDF) ESG Volatility Prediction Using GARCH and LSTM Models

Volatility Forecasting I - GARCH Models - Reider | PDF
Advertisement Space (300x250)
(PDF) Negative volatility spillovers in the unrestricted ECCC-GARCH model
(PDF) Testing for volatility interactions in the Constant Conditional ...

GARCH Models for High-Frequency Volatility | PDF | Forecasting ...

(PDF) Modelling Stock Market Volatility Using Univariate GARCH Models ...

(PDF) Modelling Volatility Dynamics of Cryptocurrencies Using GARCH Models
(PDF) Volatility spillovers under difference in the degree of market ...

004 - Modelling Volatility - Arch and Garch Models | PDF | Econometrics ...

(PDF) Estimating stock market volatility using asymmetric GARCH models
(PDF) Comparing the Volatility Spillovers among Financial Markets in ...

GARCH Models for Volatility Measurement | PDF | Volatility (Finance ...
Advertisement Space (336x280)

(PDF) Negative volatility spillovers in the unrestricted ECCC-GARCH model

(PDF) Modelling exchange rate volatility using GARCH models

(PDF) MODELING THE VOLATILITY OF EXCHANGE RATE CURRENCY USING GARCH MODEL

Volatility Spillover from the Japanese to the Vietnamese Stock Markets ...

(PDF) Predicting Stock Price Volatility Using ARCH-GARCH Models

(PDF) Volatility Spillovers from the US to Indian Stock Market: A ...

(PDF) Volatility Spillover using Multivariate GARCH Model: An ...

Price Volatility Modeling with GARCH | PDF | Autoregressive Integrated ...

(PDF) Volatility Behaviour in Emerging Stock Markets – A GARCH Approach

GARCH Volatility Modeling for Spread Returns | PDF | Coefficient Of ...
Advertisement Space (336x280)

(PDF) Assessing Volatility Patterns using GARCH Family Models: A ...

Modelling Volatility Using GARCH Models: Evidence From Egypt and Israel ...

Forecasting Volatility Using GARCH Models: Francisco Jo Ao Matos Costa ...

(PDF) Modelling Market Volatility with Univariate GARCH Models ...

GARCH Volatility Estimation via Fourier Analysis | PDF | Time Series ...

(PDF) Volatility Estimation using GARCH Family of Models: Comparison ...