
Table 2 From Modelling Market Volatility With Univariate Garch Models
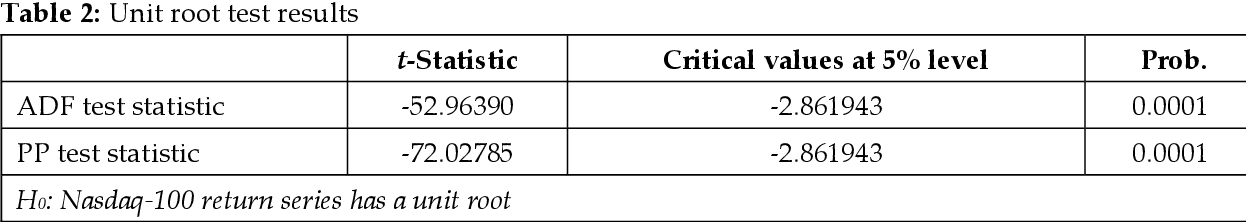
Table 2 from Modelling Market Volatility with Univariate GARCH Models ...
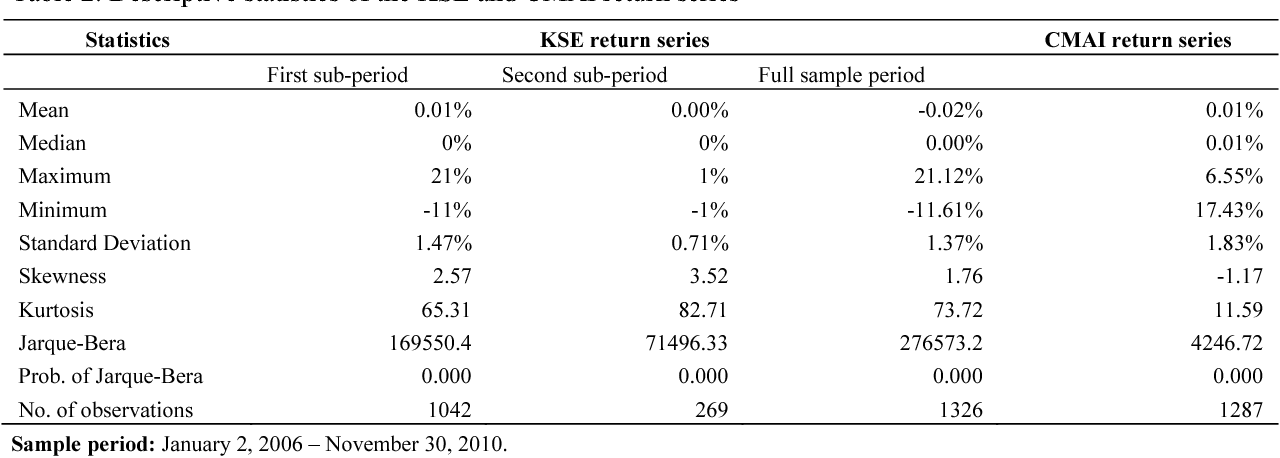
Table 2 from Modelling Stock Market Volatility Using Univariate GARCH ...
(PDF) Modelling Market Volatility with Univariate GARCH Models ...
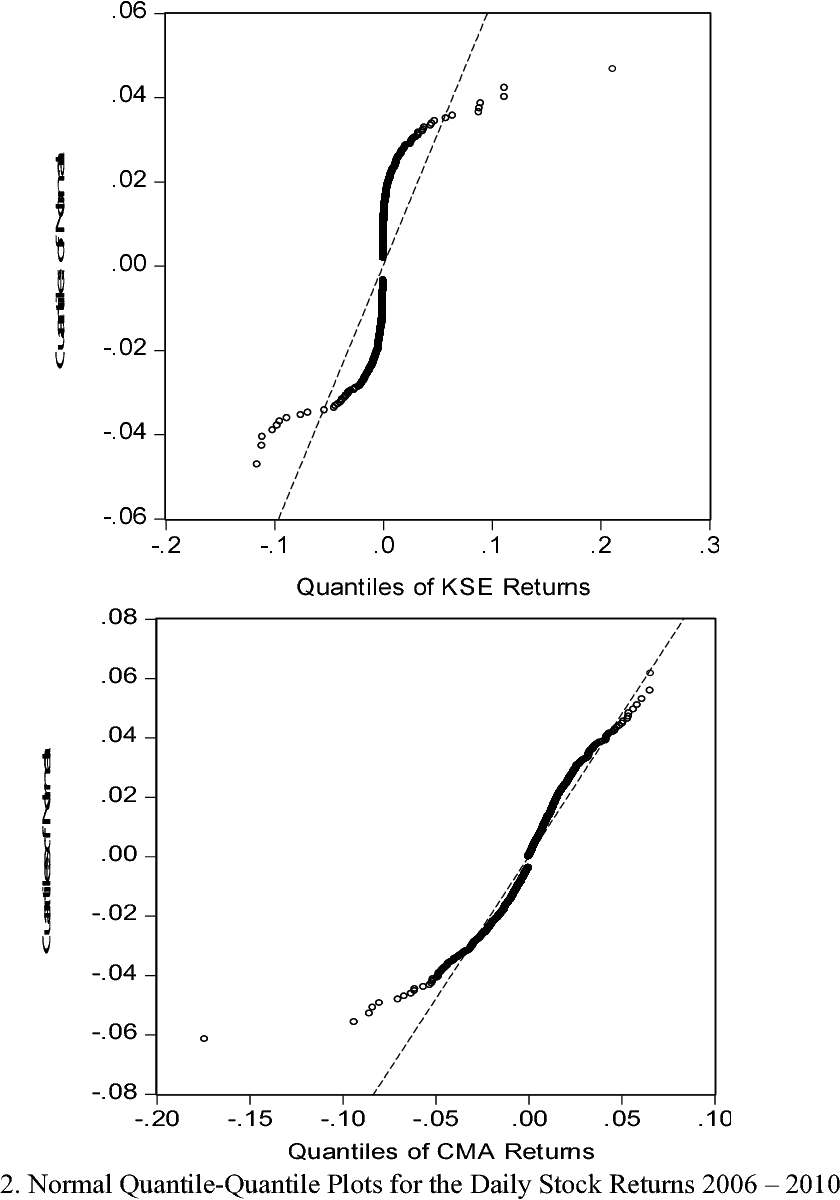
Figure 2 from Modelling Stock Market Volatility Using Univariate GARCH ...

(PDF) Modelling Stock Market Volatility Using Univariate GARCH Models ...

(PDF) Modelling Stock Market Volatility Using Univariate GARCH Models ...
(PDF) Modelling asymmetric market volatility with univariate GARCH ...
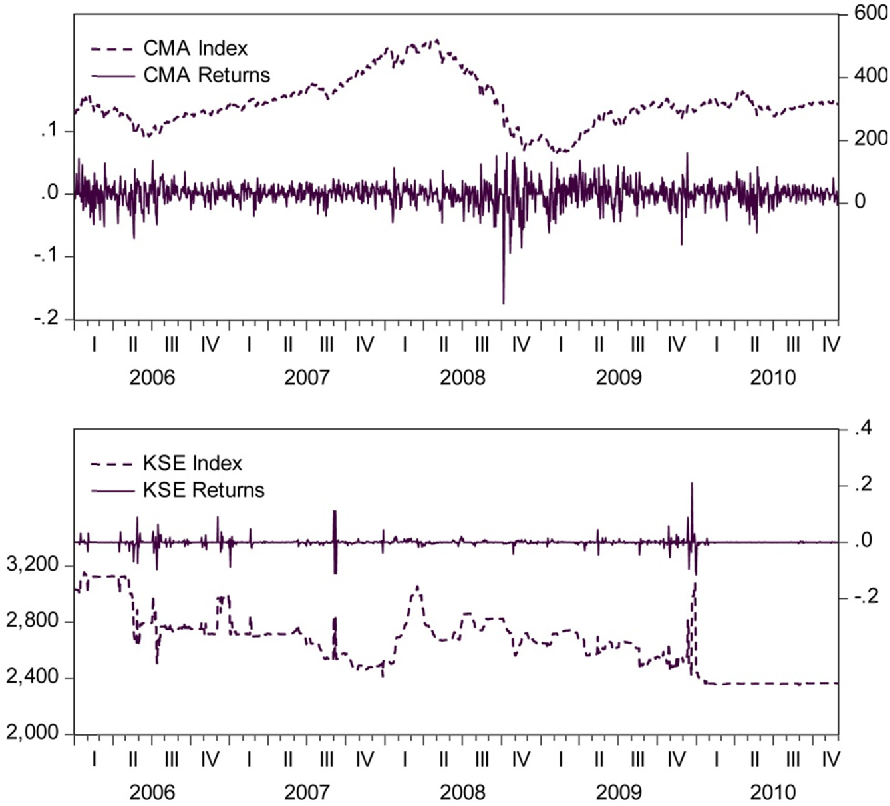
Figure 1 from Modelling Stock Market Volatility Using Univariate GARCH ...

(PDF) Modeling Stock Market Volatility Using Univariate GARCH Models ...

Table 2 from Performance of garch models in forecasting the exchange ...
Advertisement Space (300x250)

(PDF) MODELING STOCK MARKET VOLATILITY USING GARCH MODELS EVIDENCE FROM ...
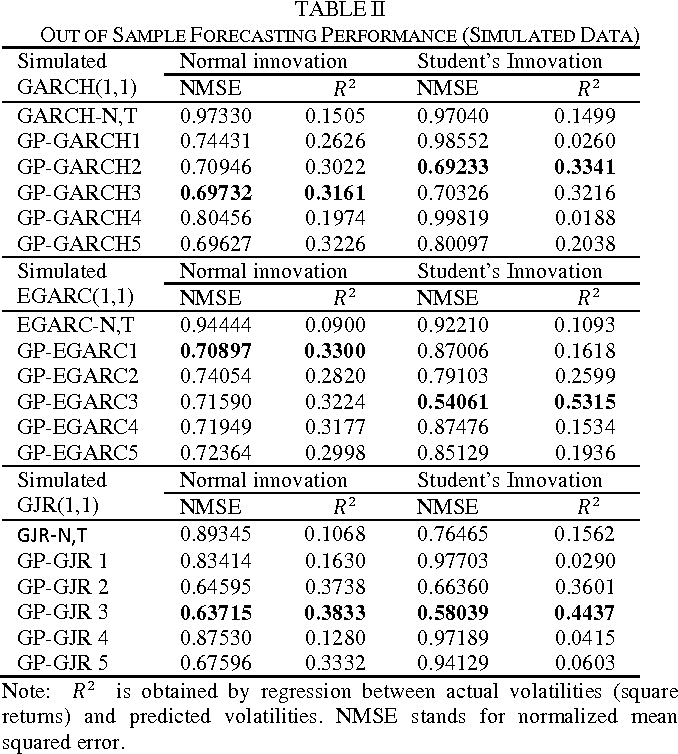
Table II from Modeling and Forecasting Stock Market Volatility by ...

GARCH modelling of stock market volatility in the US and Japanese ...

Modelling Volatility with the GARCH Model • Economics.Town

Univariate GARCH models estimations | Download Table

004 - Modelling Volatility - Arch and Garch Models | PDF | Econometrics ...
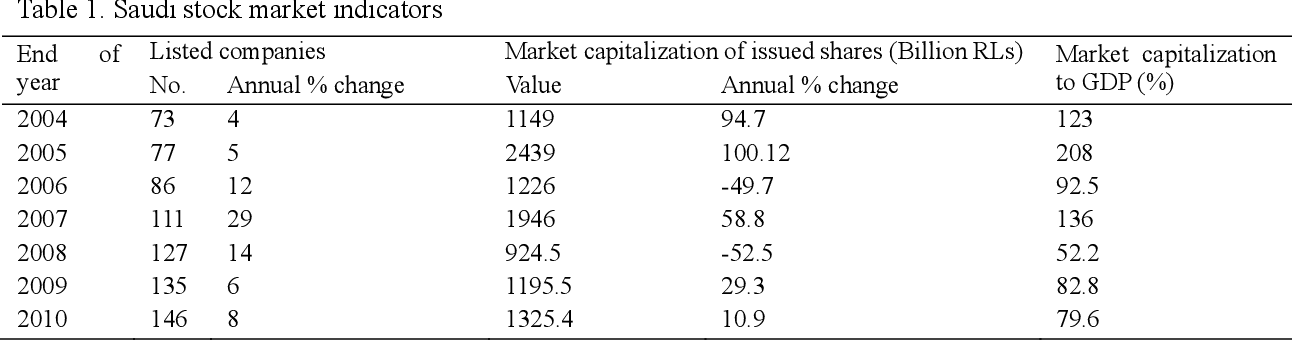
Table 1 from Stock Market Volatility in Saudi Arabia: An Application of ...

Univariate GARCH models estimations | Download Table

Modelling Volatility Using GARCH Models: Evidence From Egypt and Israel ...

COVID-19 Pandemic & Financial Market Volatility; Evidence from GARCH Models
Advertisement Space (336x280)

Table 2 from Modeling long memory volatility using realized measures of ...

(PDF) Volatility Modelling using Arch and Garch Models (A Case Study of ...

Estimated Volatilities for univariate GARCH models with skewed-t ...
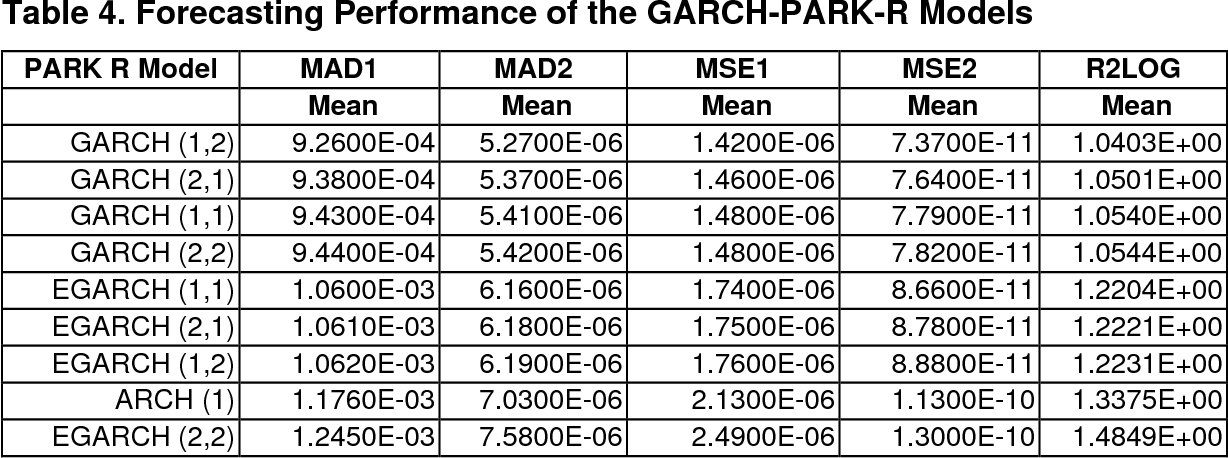
Table 4 from A Range-Based GARCH Model for Forecasting Volatility ...

GARCH models for volatility analys GARCH(1,1) | Download Table

Results of the estimation of univariate models of volatility | Download ...

Figure 1 from Modeling and Forecasting Stock Market Volatility by ...

Table 1.1 from Modeling and predicting of different stock markets with ...
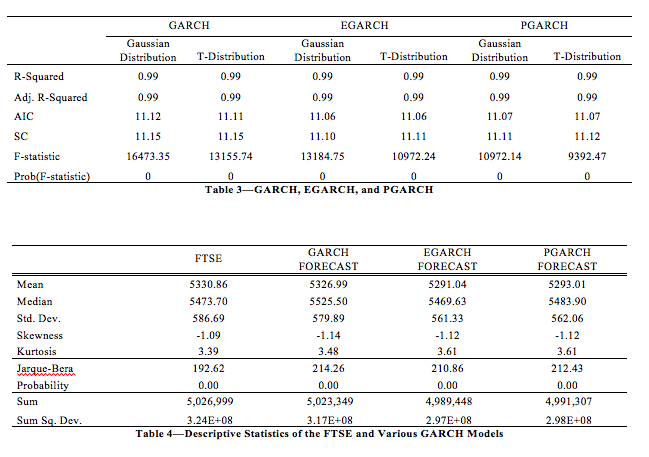
Sample | Volatility Modelling and Forecasting Using GARCH

Modelling Volatility: Arch And Garch Models – HBYRGQ
Advertisement Space (336x280)

GARCH Models for Volatility Forecasting | PDF
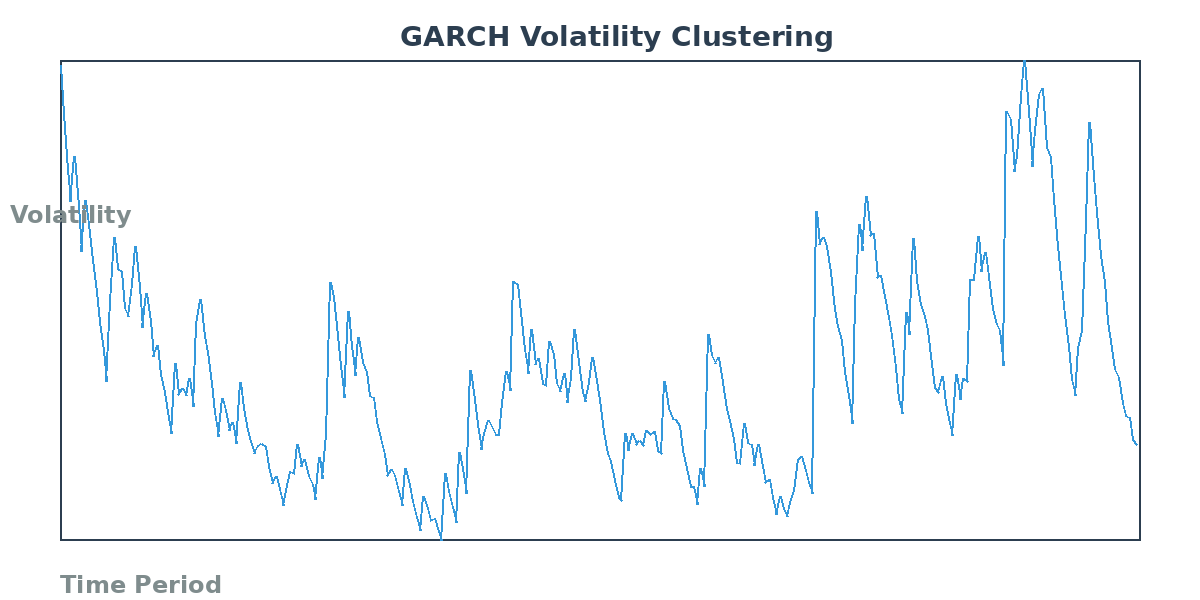
GARCH Models for Volatility Forecasting in Financial Simulations

(PDF) Univariate GARCH Model Generated Volatility Skews for the CIVETS ...

Univariate GARCH models in the studies of exchange rate risk -trade ...

(PDF) Modelling and Estimation of Volatility Using ARCH/GARCH Models in ...
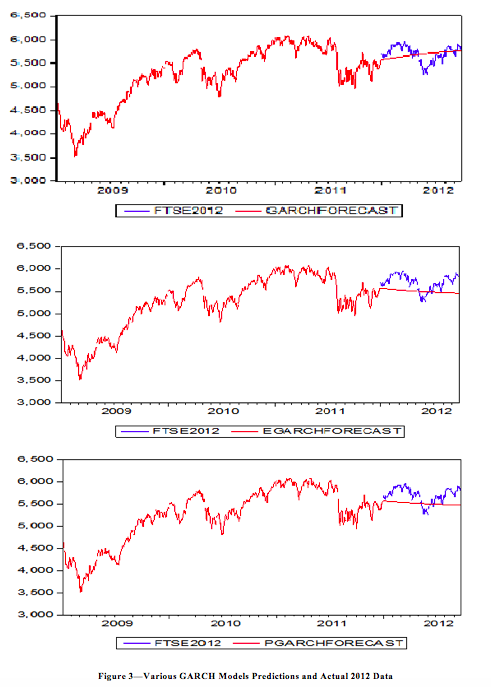
Sample | Volatility Modelling and Forecasting Using GARCH