
The Implied Volatility Surface Given By A Sabr Model With 01

The implied volatility surface given by a SABR model with σ = 0.1, α ...

The implied volatility surface given by a SABR model with σ = 0.1, α ...

The implied volatility surface given by a SABR model with σ = 0.1, α ...
5. A simulation of the implied volatility surface from Heston model ...
Implied volatility surface of the S P model using b H (t) with H = 0.7 ...
Implied volatility surface of the S P model using b H (t) with H = 0.5 ...
18: SABR calibrated volatility surface from normal implied vols by ...
12: SABR calibrated volatility surface by direct approach implied from ...
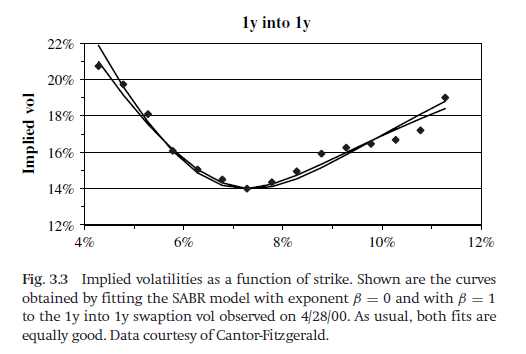
SABR Model for the Implied Volatility Smile – BSIC | Bocconi Students ...

18: SABR calibrated volatility surface from normal implied vols by ...
Advertisement Space (300x250)

18: SABR calibrated volatility surface from normal implied vols by ...

SABR Model for the Implied Volatility Smile – BSIC | Bocconi Students ...

Figure A.1: Implied volatility surface of a basket option priced with a ...

The implied volatility for the ZABR model with parameters β = 0.5, β 2 ...

Estimated implied volatility surface for model 0. The blue circles are ...
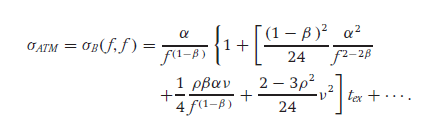
SABR Model for the Implied Volatility Smile – BSIC | Bocconi Students ...

Implied and Local Volatility Dynamics in the SABR Model - YouTube

The implied volatility surface estimated on 20050629 using a ...
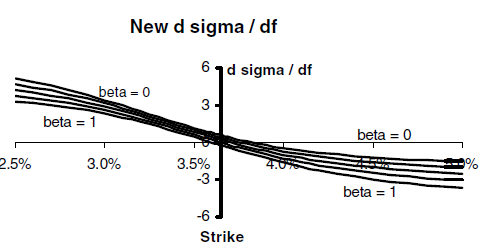
SABR Model for the Implied Volatility Smile – BSIC | Bocconi Students ...

The left subplot depicts the implied volatility surface as computed by ...
Advertisement Space (336x280)
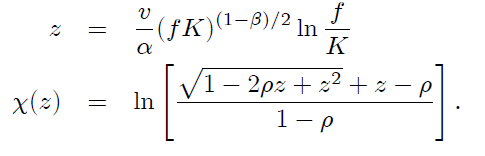
SABR Model for the Implied Volatility Smile – BSIC | Bocconi Students ...

Figure A.10: Implied volatility surface for the RAnD BS model for ...
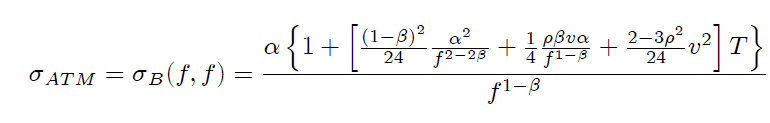
SABR Model for the Implied Volatility Smile – BSIC | Bocconi Students ...
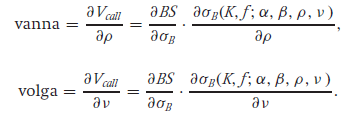
SABR Model for the Implied Volatility Smile – BSIC | Bocconi Students ...
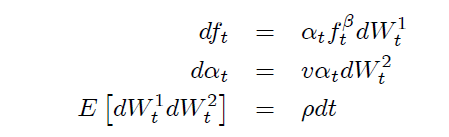
SABR Model for the Implied Volatility Smile – BSIC | Bocconi Students ...

SABR: The implied volatility model every serious quant uses. Not a ...
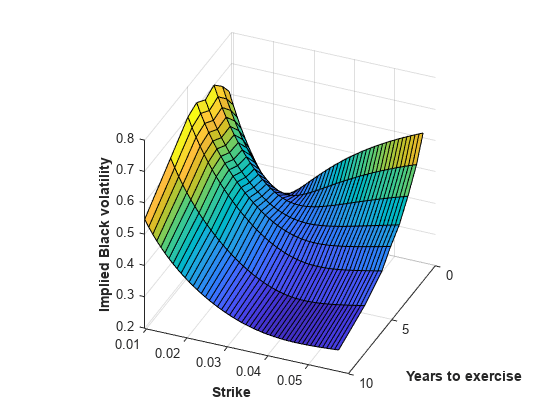
Price a Swaption Using the SABR Model - MATLAB & Simulink

8: A swaption 5Y5Y (Sep 2019) SABR volatility surface (ϑ, K ...

Indicative implied volatility surfaces for a given 1-year volatility ...

quantitative finance - SABR Model Implied Volatility in VBA - Stack ...
Advertisement Space (336x280)
Normal implied volatility surface of the S R,1/2 model. | Download ...

Implied volatility for the ZABR model when γ changes. | Download ...

Implied volatility surface for the Γ-OU martingales. | Download ...

Typical profile of the implied volatility of SP500 options as a ...

Indicative implied volatility surfaces for a given 1-year volatility ...
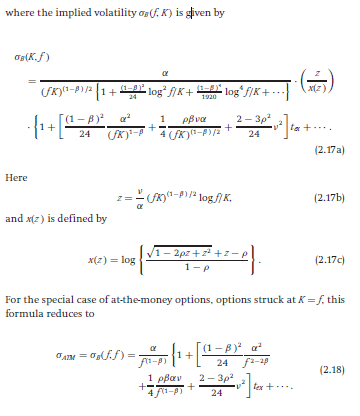
implied volatility - simple SABR model & negative strikes ...